Asset-Rich, Cash-Poor in Singapore? How a Cash-Out Bridging Loan Unlocks Your Property Equity — Fast

Singapore property representing equity unlocked through a cash-out bridging loan

Singapore property values have never been higher. For many owners, that's created a strange problem: significant wealth locked inside a home or investment property, with no easy way to access it without selling. This is the "asset-rich, cash-poor" position, and it's more common among high-net-worth Singapore property owners than most people realise.

A cash-out bridging loan is one of the fastest ways to solve it.

What Is a Cash-Out Bridging Loan?

A cash-out bridging loan is a short-term loan secured against property you already own, which releases a portion of your equity as cash, without requiring you to sell the property. Unlike a traditional refinance, bridging finance is built for speed and flexibility, funding in days or weeks rather than the months a bank refinance typically takes.

In Singapore, cash-out bridging loans are used by property owners to unlock liquidity for a business opportunity, an investment, an overseas property purchase, a family need, or simply to convert illiquid equity into working capital, all without triggering a sale.

The Asset-Rich, Cash-Poor Problem in Singapore

It's a familiar pattern: a property purchased years ago has appreciated substantially, but the owner's liquid cash position hasn't kept pace. When an opportunity or need for capital arises, the options are limited:

  • Sell the property — triggering transaction costs, taxes, and the loss of a long-term asset
  • Apply for a traditional bank refinance — slow, and often constrained by TDSR (Total Debt Servicing Ratio) rules that cap how much can be borrowed against income, not asset value
  • Do nothing — and leave the equity idle

A cash-out bridging loan sidesteps all three.

Key Features of GMG's Cash-Out Bridging Loans

FeatureDetail
Loan-to-value (LTV)Up to 80% — among the highest available for this type of lending in Singapore
TDSR requirementNone — approval is based on the asset, not income-servicing ratio
Age restrictionNone — assessed on the property, not the borrower's age
RateLowest globally for this type of asset-backed loan
Funding speedDays to weeks, versus months for a typical bank refinance

Who Uses a Cash-Out Bridging Loan?

  • Business owners needing capital for an acquisition, expansion, or working capital, without waiting on slow bank approval cycles
  • Investors wanting to redeploy Singapore property equity into other assets, including overseas property, private credit, or other investment opportunities
  • Families funding a major expense: education, an overseas property purchase, or another significant outlay, without liquidating long-held assets
  • Owners bridging a timing gap, such as buying a new property before the sale of an existing one completes

How the Process Works

  1. Valuation — the property is assessed to determine current market value and available equity
  2. Structuring — loan size, term, and LTV are structured around the borrower's specific need
  3. Approval — because assessment is asset-based rather than income-based, approval is typically faster and more certain than a conventional bank application
  4. Funding — capital is disbursed, often within days of final approval

Frequently Asked Questions

Q1: What is the maximum loan-to-value (LTV) for a cash-out bridging loan in Singapore? 

Up to 80% LTV is available, depending on the property and borrower profile, significantly higher than many conventional refinancing options.

Q2: Do I need to meet TDSR requirements for a cash-out bridging loan?

No. Cash-out bridging loans are assessed against the value of the asset, not the borrower's income-servicing ratio, so TDSR does not apply.

Q3: Is there an age limit to qualify?

No. Unlike many bank lending products, there is no age restriction on cash-out bridging loans.

Q4: How fast can a cash-out bridging loan fund?

Bridging loans are structured for speed, funding can typically be arranged in days to weeks, compared to the months a traditional bank refinance can take.

Q5: What can the funds be used for?

There are generally no restrictions, funds can be used for business capital, investment, overseas property purchases, family expenses, or any other personal or commercial purpose.
California’s AI Boom Is Building Home Equity Fast. Here’s How to Put It to Work Without Selling.

California homeowners viewing a luxury Bay Area property with the San Francisco skyline and Golden Gate Bridge in the background.

Every technology cycle that has occurred has had an effect on Silicon Valley real estate. There has been a change in housing demand during the dot-com cycle. Social media also led to a change in housing demand. With the rise in platform companies in the 2010s, there have been more changes. There are currently effects of the AI technology investment cycle on local markets. Stock awards and tenders are driving housing demand. Future IPOs might also affect some areas.

Homeowners in California might have accumulated considerable home equity through their period of owning the house. If there is any rise in the value of the property, it will make the home equity increase even more. However, this home equity might not be utilized at all. The important thing is how to make use of this quickly. Some homeowners would like to finance a new property or other businesses.

This is where the bridge loan comes into play.

California homeowners viewing a luxury Bay Area property with the San Francisco skyline and Golden Gate Bridge in the background.

The AI Boom Has Turned Home Equity Into a Bay Area Talking Point

These numbers cannot be ignored with respect to the recent increases. The median price of houses sold in San Francisco has risen to over $2 million. Experts attribute the rise to hiring of personnel in AI and corresponding financial benefits. In Santa Clara County, there have been several transactions in the luxury real estate segment. Transactions in the range of $5 million and above have increased considerably.

The trends of the down payment have followed a similar trajectory. The down payment among the wealthy Bay Area home buyers has increased from 28% prior to 2023 to around 35%. According to Realtor.com, there are indications that the cause of this trend is sales from stocks and other such liquidity events. These can be used by the buyer instead of financing for a bigger portion. Economists from Redfin have called this a “K-Shaped” housing market. The AI wealth is helping boost prices in some areas.

This is not just limited to high-end properties. According to PwC and Urban Land Institute, San Jose and San Francisco are rising markets. Their rankings in 2026 highlight the broader trends in the real estate market of that region. The impact of wealth driven by artificial intelligence seems to be extending.

The nationwide figure shows the extent of the rise in home equity. In Q2 2026, the mortgage holder equity across the United States stood at a record high of $18 trillion. This information was provided by ICE Mortgage Technology in its Mortgage Monitor report. The tappable equity is currently $11.7 trillion. This refers to the level of equity held prior to attaining the 80% loan-to-value ratio. The average equity across the U.S. stands at approximately $212,000 for each mortgaged household. California boasts some of the most expensive homes in the U.S. Additionally, it receives some of the best investments in AI technology.

California homeowners in AI markets may have built up a lot of home equity over the years. Home equity may constitute one of their biggest personal wealths. However, much of this home equity may be underutilized.

Why a Bridge Loan — Not a Sale — Is the Right Tool to Access It

Usually, homeowners have three alternatives to access their accumulated equity. They may either sell their property, refinance their home, or obtain a secondary position loan. The sale will put an end to their ownership of the property. In refinancing, there is the replacement of the current mortgage. A secondary position loan gives the borrower an opportunity to borrow from his equity without taking out another mortgage.

Selling involves relinquishing an asset that may keep increasing in value. In addition to transaction costs, selling involves paying more money for the next purchase. Cash-out refinance involves refinancing the whole first mortgage. This is likely to lead to an increase in the interest rates.

The bridge loan does not suffer from either problem. It operates in tandem with your current mortgage. It is normally a temporary, interest-only loan. Term lengths typically last between six months and two years. The loan is dependent on the current value of the property. This allows those seeking a bridge loan to:

  • Make quick moves on the new purchase: Put home equity to work in the next down payment or offer.
  • Hold onto your low mortgage: Take advantage of equity that you have without having to refinance out of an existing first mortgage at higher rates.
  • Reuse your money: Invest in private business or real estate without selling anything first.
  • Fund temporary expenses: Pay for remodeling, taxes, or cash flow requirements pending a future liquidity event.

Bridge loans usually depend on the value of the property being used for collateral and any equity available. Bridge loans usually need less paperwork to do with income than other types of refinancing loans. This means that they take less time to close.

Turning AI-Boom Equity Into a New Investment, Not Just a Bigger House

Homeowners may not be interested in having an even bigger home. Rather, they see their home equity as investible capital. This would enable them to diversify their investment portfolio, which may otherwise be concentrated in one single investment.

This is because:

  • The second criterion: Purchase a rental property or enter a new market before you sell your present house.
  • Private markets: Invest in private credit and private market options with fixed investment timeframes.
  • Capital for business: Raise capital to start a new venture, make an investment in a partnership, or raise working capital without selling any existing investments.
  • Diversification: Use the equity from your present home to diversify into other investments.

The biggest advantage here would be convenience and flexibility. A bridge loan transforms your trapped property equity into usable capital. This way, you will be able to take quick action when necessary without having to sell your property or substitute your current mortgage.

What to Weigh Before You Borrow

A bridge loan provides temporary finance, although it is usually more expensive than traditional mortgages. Not all situations will be suitable for taking out such loans. In order to proceed, one needs to take into consideration the following points.

  • Exit strategy: Create an exit plan to pay off the bridge loan well before it expires. Methods include selling, refinancing, or using other sources of money.
  • Combined loan-to-value ratio: The lender factors in your current mortgage when measuring your leverage. This will determine your equity position.
  • Cost versus opportunity: Bridge loans come at higher rates than traditional mortgages. Weigh both the costs and opportunities that it presents.
  • Market conditions: The California market has been witnessing fast appreciation in the AI niche. Consider slow appreciation when analyzing your investment plan.

Frequently Asked Questions

Q1: Is home equity in California actually higher because of the AI boom? 

In AI-led markets like San Francisco and Santa Clara County, there has been a huge increase in the price of homes. The financial gain from AI has fueled demand for housing. This has been noted in reports by Redfin, Compass, and others through 2026.

Q2: What's the difference between a bridge loan and a cash-out refinance? 

Cash-out refinancing means replacing your current mortgage with a bigger one. The drawback is that you will lose your lower interest rate. Bridge financing is different from cash-out financing in the way that bridge financing is a totally new loan.

Q3: How fast can a bridge loan close? 

Bridge loans are primarily based on the worth of the property and equity. They may not require much information on income when compared to the traditional mortgage. Hence, bridge loans close fast. Most transactions can be completed in a matter of weeks, while the traditional mortgage takes 30-45 days or more.

Q4: Can bridge loan proceeds be used for something other than buying another home? 

Yes, the money from a bridge loan is often flexible once it has been disbursed. In many cases, homeowners will invest the money in purchasing other real estate properties. Some people choose to invest their money in private markets and even private companies.

Q5: Is a bridge loan risky if California home prices moderate? 

All loans that are priced on the basis of asset value are at risk of fluctuating prices. Always borrow conservatively in relation to the total loan-to-value ratio. Moreover, always develop an exit strategy prior to the expiry of the loan period.

Private Credit Financing in Asia Pacific: How It Works and Who It’s For

Private credit financing for middle-market companies in Asia Pacific

Private credit is financing structured against a company's assets, cash flow, or a combination of both, rather than underwritten purely on a borrower's credit rating like a conventional bank loan. In Asia Pacific, it has become a primary source of growth and bridge capital for middle-market companies, particularly in Thailand, Malaysia, Singapore, and Indonesia, as regional banks tighten lending criteria.

What Is Private Credit?

Private credit is non-bank lending provided by asset managers, family offices, and specialist financing firms rather than commercial banks. Unlike a standard bank loan, which is underwritten mainly on the borrower's credit profile and financial ratios, private credit is structured against a defined collateral pool.

That collateral pool can include:

  • Hard assets — real estate, equipment, inventory, or other tangible collateral
  • Cash flow waterfalls — structured claims on a company's net operating income
  • Additional credit enhancements — guarantees, subordination structures, or covenants tailored to the deal

This asset- and structure-based approach is what allows private credit to finance transactions that don't fit inside a bank's standard credit box, including bridge financing, growth capital, and special situations.

Why Private Credit Is Growing in Asia Pacific

Banks across Asia Pacific have been tightening general lending, particularly for mid-sized companies with financing needs that fall outside standardized credit products. As that gap has widened, private credit has stepped in as an alternative source of capital for companies that have strong underlying businesses but don't fit conventional bank criteria, whether due to deal complexity, timeline, or structure.

This shift mirrors a broader global trend: as regulatory capital requirements make certain categories of lending less attractive for banks, private credit managers have absorbed a growing share of corporate financing, a pattern playing out across both developed and emerging markets, including Asia Pacific.

How Private Credit Financing Is Structured

Every private credit transaction is structured around the specific asset base and cash flow profile of the borrower. Common structures include:

  1. Bridge financing — short-term capital secured against real assets, used to fund a transaction ahead of permanent financing or a liquidity event
  2. Growth capital — financing tied to a company's expansion plans, often secured against a blend of assets and projected cash flow
  3. Special situations financing — capital for complex, time-sensitive, or non-standard scenarios that don't fit conventional lending categories

Deal sizes in this space typically range from US$10 million to US$100 million, reflecting the middle-market companies most affected by the retreat of conventional bank lending.

Private Credit Financing by Market

GMG Capital Advisory, the private credit and special situations arm of Global Mortgage Group (GMG), is currently most active in Thailand, Malaysia, Singapore, and Indonesia. Each market has distinct dynamics driving demand.

Private Credit Financing in Thailand

Thailand is currently one of GMG Capital Advisory's busiest markets for private credit. Demand is concentrated among mid-sized companies pursuing growth, acquisitions, or bridge capital ahead of a transaction, where conventional Thai bank lending criteria don't fit the timeline or structure required.

Private Credit Financing in Malaysia

In Malaysia, private credit has become an increasingly common solution for business owners and middle-market companies whose financing needs, often tied to expansion or restructuring, fall outside standard bank products.

Private Credit Financing in Singapore

As a regional financial hub, Singapore sees demand for private credit both from local companies and from cross-border transactions structured through Singapore-based holding entities, where speed and structuring flexibility matter as much as pricing.

Private Credit Financing in Indonesia

Indonesia's private credit activity is driven largely by growth-stage companies and special situations financing, where deal complexity or timeline puts transactions outside what conventional Indonesian bank lending can accommodate.

Who Private Credit Financing Is For

Private credit financing through GMG Capital Advisory is typically used by:

  • Middle-market companies with a financing need that doesn't fit standard bank criteria
  • Business owners pursuing a transaction, expansion, or restructuring on a timeline banks can't accommodate
  • Private banks and client advisors whose clients need a financing solution outside the bank's own product shelf

GMG Capital Advisory works alongside, not in competition with, private banks, arranging financing from third-party capital providers that solves the client's need while the bank retains the underlying relationship.

Key Terms Glossary

Private credit

Non-bank lending structured against a company's assets or cash flow rather than credit rating alone.

Special situations financing

Capital for complex, time-sensitive, or non-standard transactions outside conventional lending categories.

Bridge financing

Short-term capital secured against assets, used to fund a transaction ahead of permanent financing.

Middle-market company

A business generally too large for small-business lending but below the scale that accesses large-cap institutional debt markets.

Collateral pool

The combined set of assets, cash flows, and credit enhancements securing a private credit facility.

FAQ

Q1: What is private credit financing?

Private credit financing is capital provided by non-bank lenders, structured against a company's assets, cash flow, or both, rather than underwritten purely on credit rating the way a conventional bank loan is.

Q2: How is private credit different from a bank loan?

A bank loan is underwritten primarily on a borrower's credit profile and standardized ratios. Private credit is structured around a specific collateral pool: hard assets, cash flow waterfalls, and other credit enhancements, making it more flexible for deals that don't fit a bank's criteria.

Q3: What deal sizes does GMG Capital Advisory arrange?

GMG Capital Advisory typically arranges private credit and special situations financing between US$10 million and US$100 million for middle-market companies across Asia Pacific, connecting borrowers with institutional and private capital providers.

Q4: Which markets is GMG Capital Advisory most active in?

GMG Capital Advisory's busiest markets are currently Thailand, Malaysia, Singapore, and Indonesia.

Q5: Why is private credit growing in Asia Pacific?

As banks across the region tighten general lending, private credit has become an increasingly important source of growth and bridge capital for companies whose financing needs fall outside conventional bank products.

Q6: Is private credit financing more expensive than a bank loan?

Private credit is generally priced to reflect its flexibility and speed relative to conventional bank lending. Exact terms depend on the collateral structure, deal complexity, and timeline of each transaction.

Q7: How long does it take to close a private credit transaction?

Timelines vary by deal complexity and collateral structure, but a key advantage of private credit over conventional bank lending is the ability to move faster on transactions with defined timelines.

Q8: Who is eligible for private credit financing?

Eligibility is based primarily on the strength of the underlying collateral pool and cash flow rather than a standardized credit score, which is why companies with strong assets but a non-standard financing need often qualify even when a bank has declined them.

Unlocked in UK: Assessing Any UK Off-Plan Scheme Marketed Overseas — A Buyer’s Framework

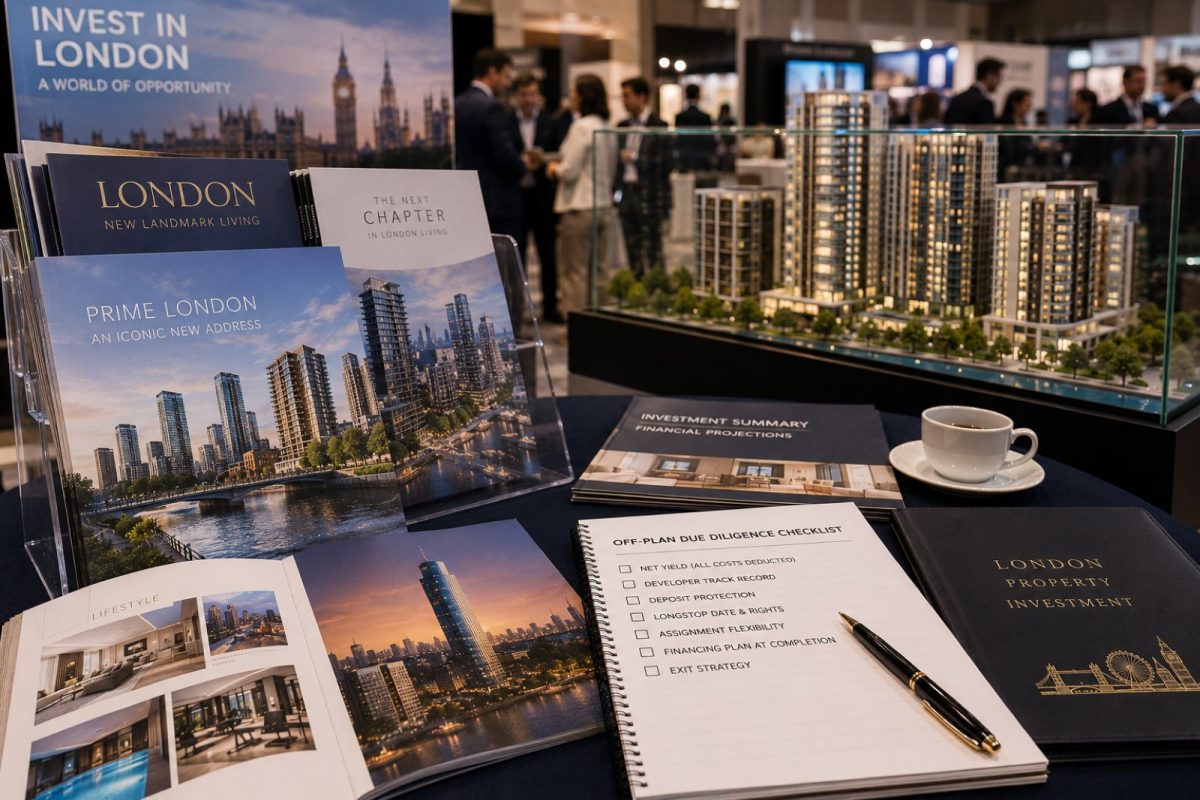
Overseas property exhibition brochures for a UK off-plan scheme, representing a buyer's framework for assessing off-plan developments

UK developments are marketed intensively across Singapore, Hong Kong, Kuala Lumpur, Dubai and beyond, typically through exhibition weekends, agent networks and glossy projections. Some of these schemes are excellent. Some are not. The difficulty for an overseas buyer is that the marketing presentation looks broadly identical either way, and the buyer is usually being asked to commit before they have seen the site, the area, or in many cases the country.

Speak to GMG about releasing equity from your UK property. Donald Klip, Co-Founder and CIO, Global Mortgage Group.

[email protected] | +65 9773 0273 | www.gmg.asia

This closing guide in the development series is deliberately generic, because the framework matters more than any individual scheme. These are the questions worth asking about any UK off-plan development marketed to you overseas, whatever the name on the brochure.

Interrogate the Projection, Not the Brochure

Rental yield projections in overseas marketing material are projections, not commitments, and they are frequently gross rather than net. A gross yield that ignores service charge, ground rent, management fees, void periods, and UK tax under the Non-Resident Landlord Scheme is not a number an investor can actually plan around. Ask for the net figure, with every deduction itemised, and treat reluctance to provide it as informative in itself.

Similarly, capital appreciation projections presented as though they were a forecast deserve scrutiny. Prime central London has spent over a decade below its 2014 peak, as this series has documented throughout. Any projection implying steady upward appreciation should be tested against that actual, recent, well-evidenced history.

"The question I would ask any agent selling a UK scheme at a Singapore or Dubai exhibition is simple: show me the net yield after service charge, ground rent, voids and UK tax, and show me your comparable evidence for the capital projection. Reluctance to answer either question tells you everything you need."
- Donald Klip, Co-Founder and CIO, Global Mortgage Group

The Questions That Actually Determine the Outcome

Beyond the numbers, the structural questions matter more than buyers realise. Is the developer established with a delivery record, or is this their first major scheme? Is the deposit protected, and under what mechanism? What is the contractual longstop date, and what are the buyer's rights if delivery slips past it? Is there any restriction on assigning the contract before completion, should circumstances change during the build period?

And critically, the financing question this series returns to repeatedly: what happens at completion if the mortgage that was assumed at exchange is not available, or the valuation comes in below the contracted price? A buyer who has thought that scenario through before exchanging, and pre-arranged a bridging contingency, is in an entirely different position from one who first considers it when the completion notice arrives.

Questions to Ask Before Exchanging on Any Overseas-Marketed UK Scheme

  • What is the net yield after service charge, ground rent, voids and UK tax, itemised
  • What is the developer's delivery record, and how is my deposit protected
  • What is the longstop date, and what are my rights if delivery slips beyond it
  • Can I assign the contract before completion if my circumstances change
  • What is my plan if the completion mortgage falls short or the valuation comes in low

About Global Mortgage Group

Global Mortgage Group (GMG) is a Singapore-headquartered cross-border real estate finance firm operating across 23+ jurisdictions, specialising in equity release, bridging loans and structured property finance for international property owners. GMG works with private clients, family offices and their advisers to unlock capital held in prime residential real estate.

Donald Klip, Co-Founder and CIO

[email protected] | +65 9773 0273 | www.gmg.asia

This is the final article in the Development guide section of GMG's Unlocked in the UK series. Speak to Donald Klip and the GMG team before exchanging on any UK off-plan purchase.

Unlocked in UK: White City, Old Oak and Outer Regeneration — Financing the Growth-Story Purchase

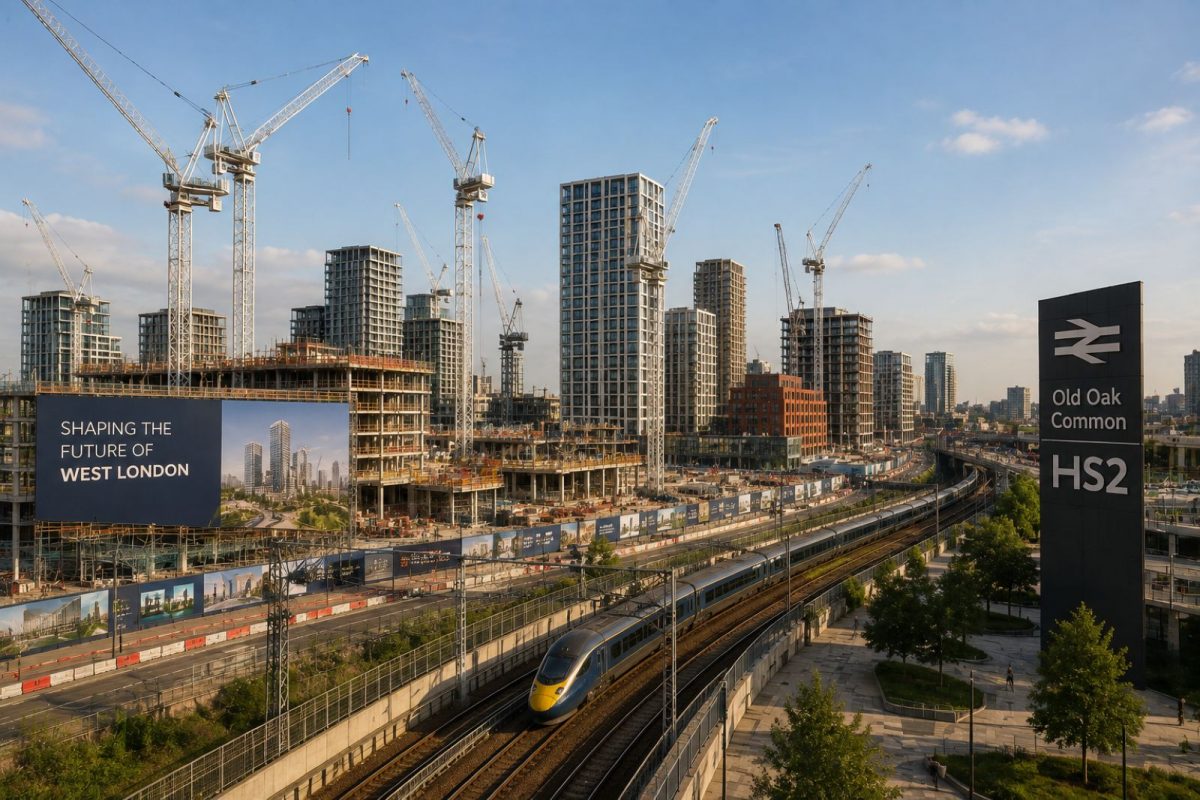
Old Oak Common construction site near HS2, representing outer-London regeneration financing for growth-story property purchases

White City, Old Oak Common and comparable outer-London regeneration zones are marketed to overseas investors on a fundamentally different basis from prime central London, in some ways echoing the marketing approach seen at Battersea Power Station. The pitch is not established prestige or scarcity; it is future growth, transport infrastructure arriving, employment moving in, an area transitioning over a ten to fifteen year horizon. Old Oak's HS2 interchange and White City's media and university cluster are the anchors of that story.

Speak to GMG about releasing equity from your UK property. Donald Klip, Co-Founder and CIO, Global Mortgage Group.

[email protected] | +65 9773 0273 | www.gmg.asia

For a patient investor, the logic is sound and the entry price is a fraction of prime central London. But growth-story purchases carry financing characteristics that differ meaningfully from buying an established asset, and international buyers marketed these schemes overseas frequently do not have those differences explained to them clearly.

Lending Against a Future, Not a Present

A lender does not lend against the regeneration story. It lends against the property's value today, in the area as it exists today, with today's comparable evidence. This is the central tension in a growth-story purchase: the buyer is paying partly for a future that has not arrived, while the lender is valuing a present that may not yet support that price.

Where infrastructure timelines slip, and major infrastructure timelines frequently do, the gap between the price paid and the value a lender will recognise can persist for years longer than the buyer anticipated. That has direct consequences at refinancing, when a facility matures and the valuation has not caught up with the purchase price, a dynamic explored further in this series' Nine Elms guide.

"The growth story might well be right. Some of these areas will transform, and the early buyers will do very well. But the lender is not underwriting the story, and the buyer needs to have the capital to hold the position long enough for the story to actually arrive. Those are two different bets and buyers routinely conflate them."
- Donald Klip, Co-Founder and CIO, Global Mortgage Group

Holding Power Is the Real Question

The practical question for a growth-story buyer is therefore not whether the area will improve, but whether they can hold the asset comfortably through the period before it does. That means financing structured for a long hold, realistic assumptions about rental income during the transition, and enough headroom to absorb a refinancing where the valuation has not moved as hoped.

Buyers who financed on the assumption of rapid appreciation, and who need that appreciation to refinance, are exposed in a way that buyers with genuine holding power are not. This is the distinction that matters most in this segment, and it is rarely the one the overseas marketing addresses.

Growth-Story Purchase Considerations

  • Lenders value the area as it is today, not as the regeneration marketing describes it
  • Infrastructure timelines slip; model a longer hold than the sales projection assumes
  • Structure financing for holding power, not for an assumed rapid appreciation
  • Model rental income realistically for the transition period, not the mature-area projection

About Global Mortgage Group

Global Mortgage Group (GMG) is a Singapore-headquartered cross-border real estate finance firm operating across 23+ jurisdictions, specialising in equity release, bridging loans and structured property finance for international property owners. GMG works with private clients, family offices and their advisers to unlock capital held in prime residential real estate.

Donald Klip, Co-Founder and CIO

[email protected] | +65 9773 0273 | www.gmg.asia

This is part of GMG's Unlocked in the UK development guide series. The final development guide covers how to assess any off-plan scheme marketed overseas.

Unlocked in UK: Branded Residences — Financing Mandarin Oriental, Four Seasons and Hotel-Branded Homes

Hotel-branded residence lobby in London, representing branded residences financing and service charge considerations

Branded residences, apartments attached to a hotel operator such as Mandarin Oriental, Four Seasons or Raffles, carrying the brand's name, service standards and management, have become one of the most heavily marketed categories in prime London to international buyers, particularly across Asia and the Gulf, where the branded residence model is already well established.

Speak to GMG about releasing equity from your UK property. Donald Klip, Co-Founder and CIO, Global Mortgage Group.

[email protected] | +65 9773 0273 | www.gmg.asia

The proposition is straightforward and genuinely attractive to a certain buyer: hotel-grade service, security, and a recognised brand, in a property you own. The financing implications, however, are less straightforward than the marketing typically conveys, and they are the part buyers most often discover late.

Service Charges and the Affordability Calculation

The defining financial characteristic of a branded residence is its service charge. Hotel-standard service, concierge, housekeeping, security, amenities, costs money, and that cost is carried by the owners through a service charge that is typically far higher than a conventional prime London mansion block. This is not a hidden fee or a criticism of the model; it is the model. But it matters for financing in a way buyers frequently overlook.

Lenders assess affordability inclusive of service charges, not just mortgage payments. A high service charge therefore directly reduces the loan amount a buyer can support, and can affect the buy-to-let calculation materially where an owner intends to let the property, since the charge is deducted from gross rental income before any yield calculation becomes meaningful.

"Buyers fall in love with the brand and the service, and they should, it is a genuinely good product for the right owner. What they miss is that the service charge sits inside the lender's affordability calculation and inside the yield maths. It is not a footnote. It is often the number that decides the deal."
- Donald Klip, Co-Founder and CIO, Global Mortgage Group

Lender Appetite and Resale

Some lenders apply additional caution to branded residences, reflecting the narrower resale market, the service charge burden, and in some schemes, restrictions on how and whether an owner may let the property independently of the operator, a consideration that matters particularly to Gulf buyers and other international purchasers drawn to this category. Buyers should establish before exchange whether their intended use, particularly short-term letting or independent letting outside the operator's rental programme, is permitted, since restrictions here affect both the lender's assessment and the owner's actual returns.

Before Buying a Branded Residence

  • Establish the full annual service charge and confirm the lender's affordability assessment includes it
  • Confirm whether independent letting is permitted, or whether letting must run through the operator
  • Understand the resale market is narrower than for equivalent unbranded prime stock
  • Model the yield net of service charge, not gross, if the property is an investment

About Global Mortgage Group

Global Mortgage Group (GMG) is a Singapore-headquartered cross-border real estate finance firm operating across 23+ jurisdictions, specialising in equity release, bridging loans and structured property finance for international property owners. GMG works with private clients, family offices and their advisers to unlock capital held in prime residential real estate.

Donald Klip, Co-Founder and CIO

[email protected] | +65 9773 0273 | www.gmg.asia

This is part of GMG's Unlocked in the UK development guide series. The next guide covers White City, Old Oak and outer-London regeneration schemes.

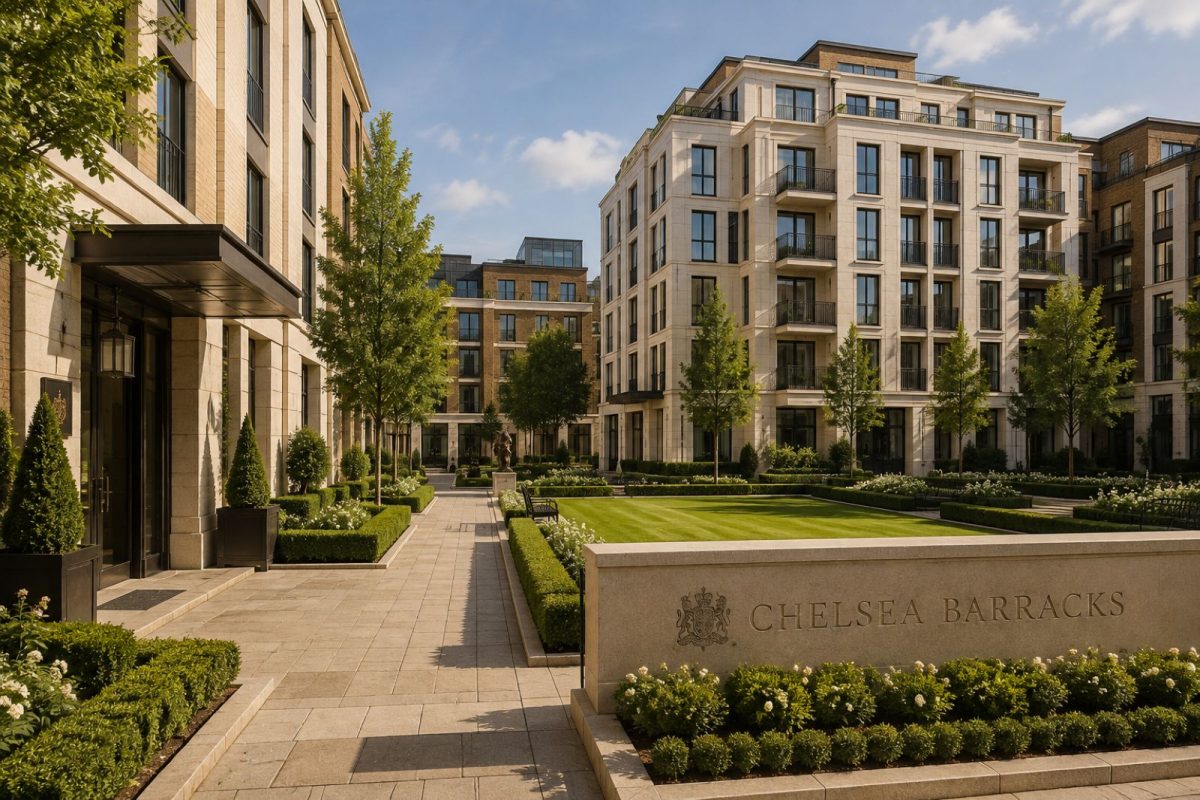
Unlocked in UK: Chelsea Barracks and Ultra-Prime New Build — Financing at the Top of the Market

Chelsea Barracks low-density development, representing ultra-prime new-build financing for principal residences and family assets

Chelsea Barracks sits at the opposite end of the new-build spectrum from the high-density towers of Nine Elms. Developed on one of the largest single sites ever released in prime central London, and backed by Qatari investment, it represents the ultra-prime end of new-build delivery: low density, high specification, and priced accordingly.

Speak to GMG about releasing equity from your UK property. Donald Klip, Co-Founder and CIO, Global Mortgage Group.

[email protected] | +65 9773 0273 | www.gmg.asia

Buyers here overlap substantially with the family office, trust and GCC purchaser profiles covered elsewhere in this series. This is not, in the main, a buy-to-let investor market. It is a market of principal residences, pieds-à-terre and long-hold family assets, frequently acquired through structures rather than in personal names.

Why Ultra-Prime New Build Finances Differently

At this price point, conventional mortgage products are largely irrelevant. Facilities are structured privately, sized against the purchaser's global balance sheet rather than a standard income multiple, and negotiated rather than selected from a product range. The relevant question is rarely whether a buyer qualifies in the conventional sense, but how a facility should be structured around an existing international wealth position, the ownership vehicle, and the family's broader leverage strategy.

"At this level nobody is filling in a mortgage application. The conversation is about how a facility fits alongside everything else the family already holds, in every jurisdiction they hold it, and which structure the property is going into. The property is the easy part."
- Donald Klip, Co-Founder and CIO, Global Mortgage Group

Structuring, and the Sharia-Compliant Dimension

Given the buyer profile, a meaningful share of transactions in this segment involve trust or corporate ownership vehicles, and for some Gulf families, a preference for Sharia-compliant financing structures rather than conventional interest-bearing debt, as covered in this series' GCC buyer guide. Both requirements are entirely standard at this end of the market, but both narrow the lender field considerably, and neither is well served by mainstream UK lending.

Buyers should also note that the conservation, heritage and covenant considerations discussed in this series' Mayfair guide apply in modified form to major prime central London new-build schemes, where estate management arrangements and long-term covenants can affect future alterations, letting and resale.

Ultra-Prime New-Build Financing Considerations

  • Facilities are privately structured against global wealth, not selected from a standard product range
  • Trust and corporate ownership vehicles are the norm rather than the exception
  • Sharia-compliant structuring is a genuine requirement for a meaningful share of buyers
  • Estate covenants and management arrangements can affect alterations, letting and resale

About Global Mortgage Group

Global Mortgage Group (GMG) is a Singapore-headquartered cross-border real estate finance firm operating across 23+ jurisdictions, specialising in equity release, bridging loans and structured property finance for international property owners. GMG works with private clients, family offices and their advisers to unlock capital held in prime residential real estate.

Donald Klip, Co-Founder and CIO

[email protected] | +65 9773 0273 | www.gmg.asia

This is part of GMG's Unlocked in the UK development guide series. The next guide covers branded residences.

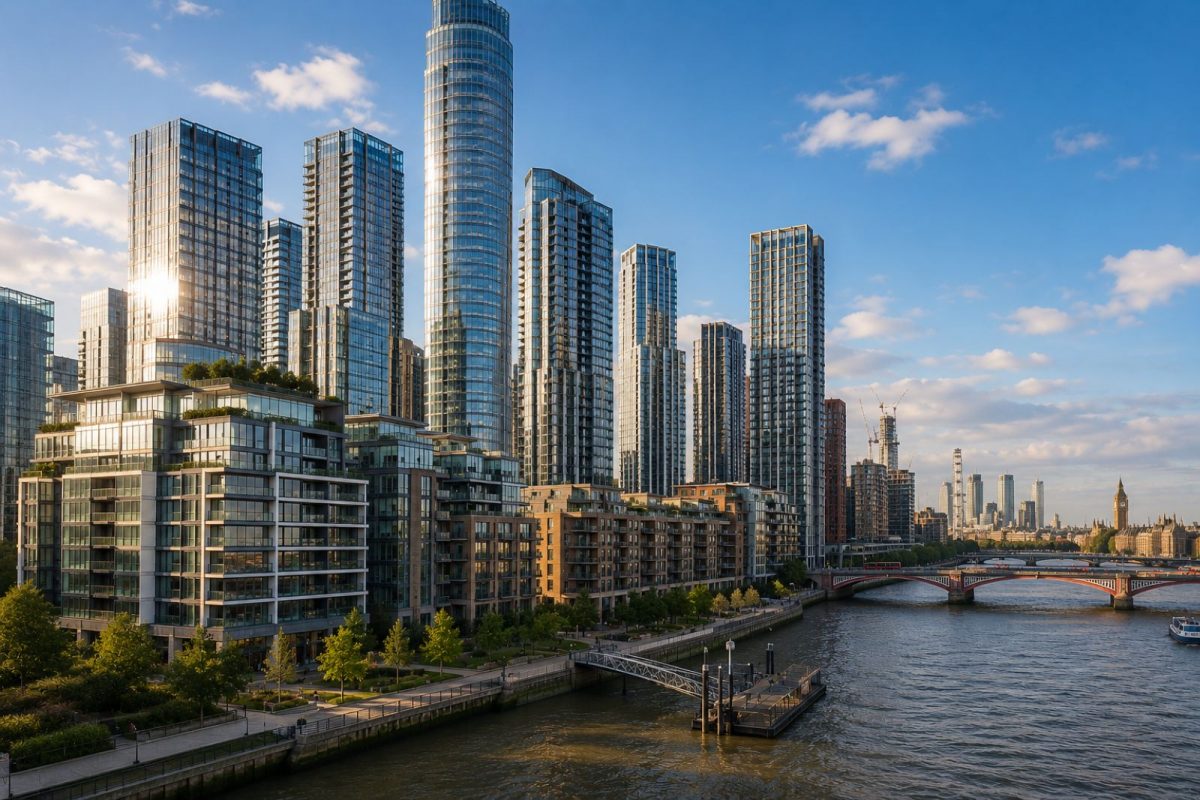
Unlocked in UK: Nine Elms and the Vauxhall Corridor — Financing in a High-Supply New-Build Market

Nine Elms and Vauxhall riverside towers, representing high-supply new-build financing considerations for overseas investors

The Nine Elms and Vauxhall regeneration corridor, stretching along the south bank between Battersea and Lambeth and anchored by the US Embassy relocation, represents one of the highest-density new-build delivery zones anywhere in London. Multiple towers from multiple developers have completed across a compressed period, and the area was marketed extensively to overseas investors throughout its delivery.

Speak to GMG about releasing equity from your UK property. Donald Klip, Co-Founder and CIO, Global Mortgage Group.

[email protected] | +65 9773 0273 | www.gmg.asia

This concentration of supply is the defining financing characteristic of the area, and it cuts both ways. For buyers, it has meant genuine choice and negotiating room. For owners looking to refinance or exit, it means competing against a large number of directly comparable units, which affects both valuation and the speed of any sale.

Why High Supply Affects Financing, Not Just Price

Lenders assess new-build apartments partly on how readily the unit could be sold if they ever needed to enforce their security. In an area where hundreds of broadly similar units may be available at any given time, that assessment is less favourable than for a scarce period property in an established postcode, and some lenders apply tighter loan-to-value limits or reduced appetite as a result.

"Supply concentration is the thing overseas investors most consistently underestimate about this part of the market. It affects your entry price, which buyers notice, and it affects your lender's appetite and your exit liquidity, which they usually do not notice until they need to refinance."
- Donald Klip, Co-Founder and CIO, Global Mortgage Group

Refinancing an Existing Nine Elms Holding

For investors who bought during the area's marketing push and now hold completed units, refinancing conversations tend to centre on two things: whether the current valuation supports the loan amount required, and whether the rental income the unit generates is sufficient for a buy-to-let assessment in the current rate environment. Owners holding multiple units across the corridor should consider the portfolio-level refinancing approach discussed elsewhere in this series rather than treating each unit as a separate application.

Where a valuation has not performed as originally hoped, an owner facing a maturing facility has a genuine strategic decision rather than a purely administrative one: inject capital to refinance at a lower loan-to-value, sell into a competitive market, or restructure. That decision benefits from being made deliberately and early, rather than in the final weeks before a facility expires, a discipline that applies as much to UK property investors generally as it does to owners specifically in this corridor.

Nine Elms and Vauxhall Financing Considerations

  • High comparable supply affects lender appetite and exit liquidity, not just the entry price
  • Some lenders apply exposure limits restricting units financed within a single scheme
  • Owners of multiple units should explore portfolio-level refinancing rather than unit-by-unit renewal
  • Address maturing facilities early, particularly where valuations have not performed as expected

About Global Mortgage Group

Global Mortgage Group (GMG) is a Singapore-headquartered cross-border real estate finance firm operating across 23+ jurisdictions, specialising in equity release, bridging loans and structured property finance for international property owners. GMG works with private clients, family offices and their advisers to unlock capital held in prime residential real estate.

Donald Klip, Co-Founder and CIO

[email protected] | +65 9773 0273 | www.gmg.asia

This is part of GMG's Unlocked in the UK development guide series. The next guide covers Chelsea Barracks and the ultra-prime new-build segment.

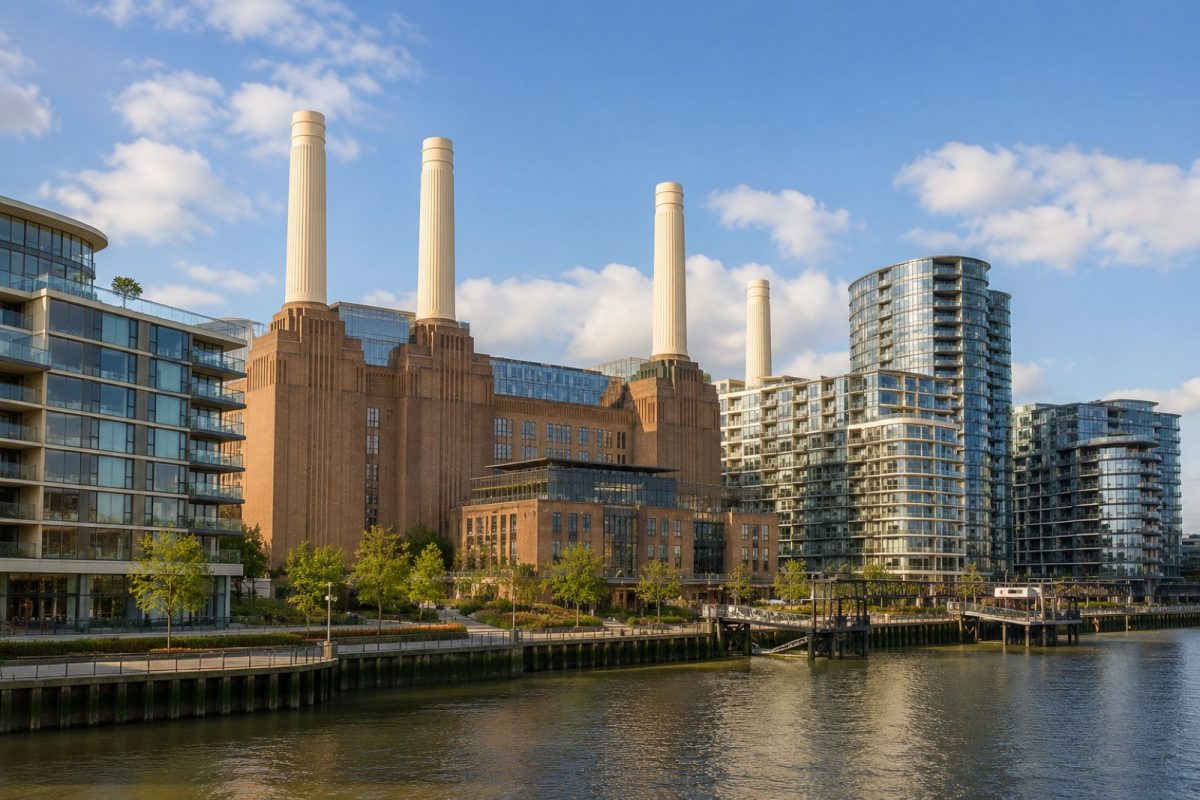
Unlocked in UK: Battersea Power Station — Financing a Purchase in London’s Largest Regeneration Scheme

Battersea Power Station development riverside, representing financing considerations for buyers across its phased delivery

Battersea Power Station has become one of the most recognisable names in London property marketing overseas, particularly across Southeast Asia, where the scheme was heavily promoted to Malaysian, Singaporean and Hong Kong investors from its earliest phases onward. For many international buyers, it was their first exposure to UK off-plan investment, and for a significant number it remains the only UK property they own.

Speak to GMG about releasing equity from your UK property. Donald Klip, Co-Founder and CIO, Global Mortgage Group.

[email protected] | +65 9773 0273 | www.gmg.asia

The development's scale and phased delivery over more than a decade means buyers across different phases hold very different positions. Someone who exchanged on an early phase years before completion faces an entirely different financing question from a buyer purchasing a completed resale unit today, and the two should not be treated as the same transaction.

The Off-Plan Exchange-to-Completion Gap

The single most consequential financing issue for off-plan buyers at Battersea, and at large phased schemes generally, is the gap between exchange and completion. A buyer who exchanged contracts years ago committed to a price, and paid a deposit, based on their circumstances and the lending environment at that time. By the time the unit is ready and completion is called, their income, their residency status, sterling's exchange rate, and the mortgage market itself may all have shifted materially.

This creates a recurring and genuinely stressful scenario: a buyer contractually committed to complete, facing a developer deadline measured in weeks, discovering that the mortgage they assumed would be available is not, or is available only at a materially lower loan amount than expected. Bridging finance exists precisely for this gap, allowing the buyer to complete on time and then refinance onto a longer-term facility once the immediate deadline has passed.

"The off-plan buyer's problem is that they made a decision years ago and the completion notice arrives against today's lending market. Nobody plans for that gap at the point of exchange, because at exchange it feels a long way off. It never is."
- Donald Klip, Co-Founder and CIO, Global Mortgage Group

New-Build Valuation and Lender Appetite

Buyers should also understand that a lender's valuation at completion is an independent assessment, and will not automatically match the price agreed at exchange. Where a valuation comes in below the contracted price, the buyer must fund the shortfall from their own resources, since the lender will advance against the valuation rather than the purchase price. This is a general feature of off-plan purchasing rather than anything specific to this scheme, but it bites hardest at large developments where many units complete in the same window.

Some lenders also apply exposure limits to individual developments, restricting how many units in a single scheme they will lend against. For a buyer at a very large development, this can narrow the available lender pool in ways that are not obvious until an application is already underway.

Questions for a Battersea Power Station Buyer

  • Which phase, and how long between exchange and the expected completion date
  • Has income, residency or currency position changed materially since exchange
  • Is bridging pre-arranged in case the completion mortgage falls short or falls through
  • Has the lender confirmed they have appetite for this specific development

About Global Mortgage Group

Global Mortgage Group (GMG) is a Singapore-headquartered cross-border real estate finance firm operating across 23+ jurisdictions, specialising in equity release, bridging loans and structured property finance for international property owners. GMG works with private clients, family offices and their advisers to unlock capital held in prime residential real estate.

Donald Klip, Co-Founder and CIO

[email protected] | +65 9773 0273 | www.gmg.asia

This is part of GMG's Unlocked in the UK development guide series. The next guide covers Nine Elms and the wider Vauxhall regeneration corridor.