Unlocked in Malaysia: Introducing Malaysian Bridging Loans to Unlock the Equity in Malaysian Real Estate

Kuala Lumpur skyline representing Malaysian bridging loans for property equity release, land, commercial real estate and development financing

Malaysia is sitting on an enormous amount of real estate equity: land, commercial buildings, industrial sites, development projects and family-held assets across the country. Until now, there have been very few good options for turning that equity into liquidity.

Banks lend against income and paperwork, on their timeline. Owners who need capital quickly, against an asset they already own, have had little to turn to.

Working closely with our capital providers, we’ve built a Malaysian bridging loan solution to change that: fast, asset-backed funding for property owners, investors and developers who want to unlock the value in their real estate.

In Malaysian property, the problem is rarely the asset. It’s access to liquidity at the moment it’s needed.

A bank facility needs redeeming before a refinancing completes. An auction win has a 90-day completion window. A developer needs a cash bridge until a sale closes or a project loan is released. An owner with land or a building free of debt wants capital for the next opportunity. In each case, a conventional bank loan runs on a timeline, or a set of criteria, that doesn’t fit.

That’s the gap this offering is built to close.

What is a bridging loan?

A bridging loan is short-term, asset-backed financing that “bridges” you from where you are to where you need to be: a sale, a refinancing, a project milestone or a completion deadline. It is typically secured on property, repaid from a defined exit, and structured around speed and certainty rather than the lowest possible rate.

What GMG’s Malaysian bridging loans cover

We finance all types of real estate, anywhere in Malaysia, from Kuala Lumpur and Johor Bahru to Penang, Ipoh, Kuching, Kota Kinabalu and smaller cities and towns where banks often lose interest.

  • Property types: residential, commercial, industrial, retail, hospitality, development sites and land (including agricultural, plantation and raw land), plus data centres
  • Locations: major cities and secondary markets across Peninsular Malaysia, Sabah and Sarawak
  • Loan size: US$500K and above
  • Tenor: 12-24 months
  • Security: First-charge on the property
  • Currency: RM and SGD options
  • Indicative timeline to terms: 72 hours

When a Malaysian bridging loan makes sense

1. Unlocking equity in assets you already own. 

You own land, a commercial building or an industrial property with significant equity, but no simple way to get liquidity from it. A bridging loan lets you borrow against the asset to fund a new investment, a business need or a transition, without selling.

2. Redeeming an existing facility. 

You want to move out of a bank loan, but the new lender’s process will take longer than your redemption deadline. A bridge clears the old facility and gives you time to refinance properly.

3. Property auctions. 

Auction purchases come with a hard deposit and a short window to complete. Bridging finance can fund the balance when bank approval can’t land in time.

4. Developer and project cash flow. 

Cover working capital or land payments until a sale, a project loan drawdown or a partial exit lands.

5. Data centre financing. 

Malaysia, and Johor in particular, has become one of Southeast Asia’s hottest data centre markets, with demand driven by cloud and AI. Sites need land, power and construction capital long before tenants and long-term financing arrive. We provide bridge and short-term capital for land acquisition, site development and facility build-out, until permanent financing or an exit is in place.

6. Land deals in big cities and small. 

Banks can be reluctant on land and on assets outside the main cities. We look at the asset, the location and the exit, and we don’t turn a deal away just because it isn’t in KL.

7. Time-sensitive acquisitions. 

Move on a motivated seller before a slower competitor can.

8. Cross-border investors. 

If you’re a Singapore, Hong Kong or international investor buying in Malaysia, local bank processes can be slow and paperwork-heavy. We work across borders every day.

Why GMG

Global Mortgage Group is a Singapore-headquartered, real estate finance firm operating across 23+ markets. Because so little liquidity has been available against Malaysian real estate, we built this offering with our capital providers so that the lenders behind it understand the market, the assets and the exit. Our team of institutional professionals, look at the asset, the exit and the story, not just a template credit box.

What we look for in a good bridging deal

  • A clear, credible exit (sale, refinance or repayment event)
  • Quality security with a supportable valuation
  • A defined timeline and purpose
  • A sponsor or borrower with a track record
  • For data centres: power availability, land title and tenant or off-take position

If your deal has these, we’d like to hear about it.

Frequently asked questions

Q1: How fast can a Malaysian bridging loan be arranged?

As fast as a few weeks but typically between 4-6 weeks from termsheet. 

Q2: What property types do you accept as security?

Almost all types of real estate across Malaysia: residential, commercial, industrial, hospitality, development sites and land, in major cities and smaller markets alike. We also finance data centres, including in Johor and the Klang Valley. 

Q3: Do you finance data centres in Malaysia?

Yes. We provide bridge and short-term financing for data centre land, development and facilities, including in Johor, where demand is growing fastest. Contact us with the site, power status, tenant position and exit.

Q4: Can I borrow against property I already own outright?

Yes. If you own land or a building with significant equity, a bridging loan can release liquidity against it without a sale. 

Q5: Do you lend to foreign borrowers?

Yes, absolutely. 

Q6: How much does a bridging loan cost?

Pricing depends on the asset, loan-to-value, tenor and exit. Contact us for an indicative quote on your specific deal.

Q7: What’s the difference between a bridging loan and a normal bank loan?

Bridging loans are shorter, faster and more flexible, but typically carry a higher cost. They’re designed to be repaid from a defined exit rather than held long term.

Talk to us about your deal

Send us the basics (location, asset, loan amount, purpose and exit) and we’ll come back with honest feedback quickly.

Donald Klip
Head, GMG Capital Advisory
[email protected]
WhatsApp: +65 9773-0273
Book a Call: https://calendly.com/gmgdonald/15min
Australia’s Cash Rate Hits a 15-Year High: How to Unlock AUD 2M of Equity Without Refinancing Your AUD 5M Bank Loan

Australian residential property representing second mortgage financing and equity release for overseas property owners

If you own Australian property from overseas and need extra capital, you do not have to refinance your whole bank loan. A second-ranking mortgage can release a further AUD 1M–5M against your existing equity while the original bank facility stays exactly where it is. Global Mortgage Group (GMG) helps overseas-based borrowers, including Australian expats and permanent residents, arrange this, often without requiring Australian income or credit, subject to assessment of the property and the transaction.

What the RBA just did

On 29 September 2026, the Reserve Bank of Australia raised the cash rate by 25 basis points to 4.60%. The board's vote was unanimous. It is the fourth increase of 2026 and takes the cash rate to its highest level in 15 years, since late 2011.

Banks are already passing it on. Commonwealth Bank has announced a 0.25% increase to its variable home loan rates from 9 October, and Macquarie follows from 15 October. The RBA has also said it will keep raising rates if needed to bring inflation back to target. Q3 inflation data is due on 28 October, a week before the board next meets, and some economists are pencilling in another 25bp increase.

For an overseas investor who needs extra capital, it raises a hard question: is it sensible to refinance a large facility at today's rates, or at even higher rates in future, just to access a smaller amount of new money?

The dilemma: lots of equity, but the wrong moment to refinance

Many international owners of Australian property are in the same position. The asset has grown in value. The equity is substantial, even as valuations have recently softened. But the existing bank loan was written at a different point in the rate cycle, and replacing it means repricing every dollar.

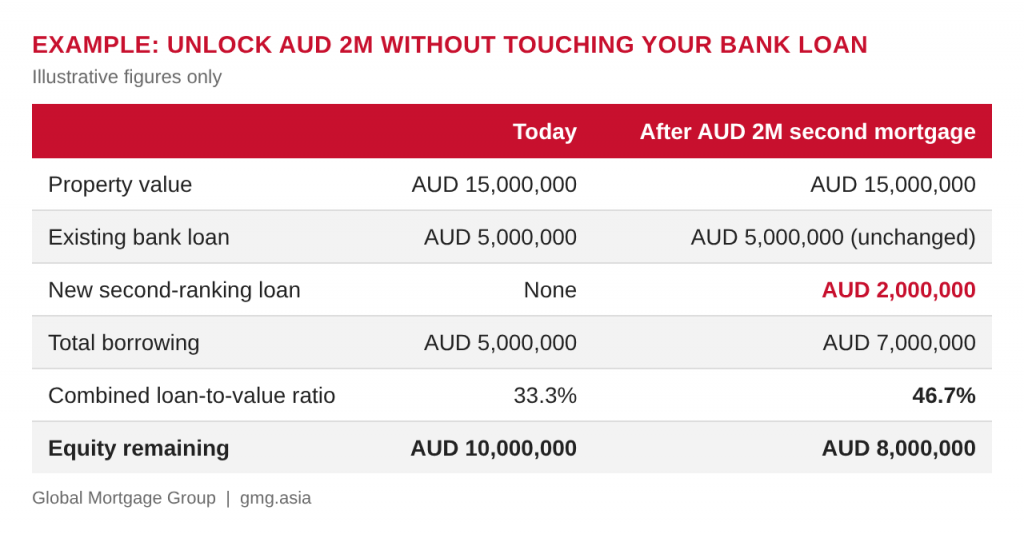
Here is a typical example:

The investor has AUD 10 million of equity and needs AUD 2 million. Even after the new loan, the combined borrowing sits below half of the property's value.

Why refinancing the whole facility may not make sense

Refinancing the existing AUD 5M loan into a new AUD 7M facility has several consequences worth weighing:

  • Everything reprices. The full AUD 7M moves to today's rate, not just the extra AUD 2M. Each 1.00 percentage point of rate is worth about AUD 70,000 a year on AUD 7M, versus AUD 20,000 on AUD 2M.
  • Fixed-rate and exit costs. Breaking a fixed-rate loan early or discharging a facility can trigger fees.
  • Bank assessment. Mainstream lenders typically assess income, credit history and serviceability. For overseas-based owners with foreign income, that process can be slow or restrictive.
  • Timing. A full refinance means a new valuation, new credit approval and a full settlement process, even when you only need a fraction of the equity quickly, whether to seize an investment or business opportunity or to meet expenses.

The alternative is a second-ranking mortgage: a loan secured against the same property that ranks behind your bank mortgage, leaving that loan in place on its existing terms. A bridging loan secured this way will usually carry a higher rate than a first-ranking bank loan, so the right comparison is blended cost: the existing loan at its current rate plus the new loan at its rate, against the whole amount at a new bank rate.

How GMG can help

We regularly consider situations that fall outside the usual lending parameters:

  • Smaller loan amounts of AUD 1M–5M, often below the minimums that some specialist or institutional lenders will accept
  • Second-ranking mortgages where appropriate, even if the first-ranking loan is provided by a non-bank lender
  • Overseas-based borrowers, including Australian expats and permanent residents (PRs). Typically no Australian income or credit required
  • Property held in personal names, not necessarily through companies, trusts or SPVs
  • Flexible use of funds, including business expenses and investments within and outside Australia

Each case is assessed on the property, the existing facility, use of funds, the combined loan-to-value ratio and the exit strategy. Terms vary by deal.

How it works

  1. Share the basics. Property location and estimated value, existing loan balance and lender, amount needed, intended use and exit plan.
  2. We assess the structure. We check how a second-ranking position would work alongside your existing bank mortgage, including any requirements of the first lender.
  3. Indicative terms. We take the opportunity to suitable lenders and come back with indicative terms and the blended-cost comparison against refinancing.
  4. Valuation, legal and settlement. A valuation and legal documentation follow, with funds released at settlement.

Who this suits

  • Overseas owners of Australian property with significant equity and an existing bank loan they would prefer not to disturb
  • Australian expats and PRs living abroad without local income or credit footprint
  • Investors and business owners who need capital in a defined window, for opportunities inside or outside Australia
  • Private banking and wealth advisers with clients in this position. Refer the opportunity and keep the client relationship

Who it may not suit

If you need a very long-term facility at the lowest possible rate and you qualify for mainstream bank credit, refinancing may be the better route. We will tell you if that is the case.

Frequently asked questions

Q1: What is Australia's cash rate now? 

The RBA cash rate is 4.60%, set on 29 September 2026. It is the fourth increase of 2026 and the highest level in 15 years.

Q2: Can I borrow against my Australian property without refinancing my existing bank loan? 

Often, yes. A second-ranking mortgage allows you to borrow additional funds against the same property while your existing bank loan stays in place. Feasibility depends on the property, the combined loan-to-value ratio and the terms of the first mortgage.

Q3: Can overseas residents, expats and PRs borrow against Australian property?

Yes. GMG works with overseas-based borrowers, including Australian expats and permanent residents. Typically, no Australian income or credit is required, though the property and transaction are assessed.

Q4: What loan sizes do you consider? 

We look at loans from AUD 1M to AUD 5M, including amounts below what some specialist or institutional lenders will consider.

Q5: Does the property need to be held in a company or trust? 

No. Properties can often be owned in personal names, not necessarily through companies, trusts or SPVs.

Q6: What can I use the funds for? 

Use of funds is flexible, including business expenses and investments within and outside Australia.

Q7: Is a second mortgage more expensive than a bank mortgage? 

It typically carries a higher rate than a first-ranking bank loan. The right test is blended cost over the period you need the funds, compared with refinancing the entire facility at today's rates. We run both comparisons for you.

Talk to us

If you have Australian property, an existing bank loan and a funding need, tell us the numbers and we will tell you whether a second-ranking structure makes sense.

Donald Klip, Head of GMG Capital Advisory

Book a 15-minute call: https://calendly.com/gmgdonald/15min 
Email: [email protected] 
WhatsApp / mobile: +65 9773-0273

59% of Singapore’s Wealthy Have a Cash Problem. Here’s How to Fix It Without Selling

59% of Singapore's Wealthy Have a Cash Problem. Here's How to Fix It Without Selling

This article builds on the Manulife and FT Longitude research featured in the Financial Times: "For Singapore's wealthy, longevity and liquidity go hand in hand". Survey figures below are from that piece. 

59% of Singapore's high-net-worth individuals say sustaining income and liquidity over a longer lifespan is a top financial concern, according to a new Manulife and FT Longitude survey. Not investment returns. Liquidity. 

It is the problem we hear most from property owners: plenty of wealth, but locked in a home, a shophouse or a portfolio they would rather not sell. A Singapore bridging loan is one way to release that cash while keeping the asset. This guide explains how it works, who it suits, how it compares with a bank loan, and what to plan for before you borrow. 

The liquidity paradox: wealthy on paper, short of cash 

Manulife surveyed 1,000 high-net-worth and mass affluent individuals across 11 markets in April and May 2026, including 250 in Singapore. Singapore respondents worried about liquidity more than the wider sample did: 

  • 59% named sustaining income and liquidity over a longer lifespan as a top concern, against 54% across the full sample 
  • 55% named rising healthcare and long-term care costs, against 52% 
  • One in four plan to start a new venture after their main career, which needs deployable cash 
  • Singapore respondents were the most likely in the region to plan to work beyond the traditional retirement age 

The FT feature calls this the liquidity paradox. Much of the wealth sits in businesses, property and other assets that cannot be divided or sold quickly. As Andreas Mettenberger of Synpulse puts it, owners "do not necessarily want to sell out of the assets they have." 

There is good reason for that. A forced sale can undermine succession plans and trigger tax consequences, and it means giving up an asset that may keep appreciating or produce income. For many owners the real question is not how much they are worth, but how to get cash out of what they own without selling it. 

The FT and Manulife piece reaches the same conclusion: "the ultimate test of liquidity is not the size of the balance sheet, but its flexibility and resilience under pressure." Its recommended tool is life insurance. Frank O'Neill, Chief Product Officer at Manulife Singapore, says it "provides liquidity at critical moments and brings certainty to the transfer of wealth." That is a valid part of a liquidity plan, and the article also urges families to hold assets they can access quickly. For owners whose largest asset is property, borrowing against it is a complementary route, covered below. (Manulife's views are quoted from the article; they do not refer to bridging loans.) 

How a Singapore bridging loan works 

A bridging loan is short-term financing secured against property, typically for 6 to 24 months. Instead of repaying principal every month, you pay interest only, and settle the loan at the end of the term from a planned exit. Because the lender looks at the property and your exit plan rather than your income, approval is usually faster than at a bank. 

Key features 

  • Interest-only: monthly outlay is lower than a bank loan that amortizes principal, which matters most for older borrowers facing shorter loan tenures 
  • No TDSR: the Total Debt Servicing Ratio does not apply. Assessment centers on the value of the property and your exit plan, not income proof 
  • No age restriction: banks often cap lending by age or tenure; asset-backed private lenders such as GMG do not 
  • Fast funding, with certainty: approval and disbursement are typically much faster than a bank mortgage 
  • Up to 80% loan-to-value: available against condos, landed homes, Good Class Bungalows (GCBs), shophouses and other property types [confirm this cap before publishing] 
  • Open to Singaporeans, PRs and foreigners 
  • Cost: indicative interest rates of 5.5% to 7% depending on LTV and property type, subject to credit approval 

Typical exit strategies 

Because lenders focus on how you will repay, a clear exit is central to every application: 

1. Sell the property or another asset at the end of the term 

2. A liquidity event, such as a business sale, an investment realization or an inheritance 

3. Refinance into bank financing once the reason for the bridge has passed 

Bridging loan vs bank loan for older borrowers 

On a $5M loan against a $7M Singapore home, a 50-year-old borrower pays roughly $22,900 a month on a 1-year interest-only bridging loan at 5.5%, against about $48,300 a month on a 10-year bank loan at 3% with principal and interest. That is $25,400 a month less in cash outflow, though the bridging loan must be repaid or refinanced at the end of its term. 

ComparisonBridging loanBank loan
Able to borrow at 65YESNO
Loan amount$5,000,000$5,000,000
Property value$7,000,000 (about 71% LTV)$7,000,000 (about 71% LTV)
Rate (illustrative)5.5%3%
StructureInterest onlyPrincipal + interest
Term1 year10 years
Monthly paymentabout $22,900about $48,300
Paid in the first 12 monthsabout $275,000 (interest)about $579,000 (interest + principal)
Principal outstanding at end$5,000,000, due at exitFully repaid
Approval basisProperty value and exit planIncome, TDSR and age limit

The comparison is about cash flow, not total cost. The bank loan is cheaper per dollar borrowed and clears the debt, but it demands a much larger monthly payment and, for older borrowers, is often limited by age caps and shorter tenures. A bridging loan trades a higher rate for lower outflow and speed, on the condition that you have a credible way to repay the principal. 

Illustrative example only. Rates, LTV and terms vary by property and borrower, and a 3% bank rate and 71% LTV may not be available to every borrower. 

Who it suits, and the risks to weigh 

A bridging loan fits owners who hold valuable property, need cash for a defined purpose, and have a credible way to repay. 

  • Older homeowners who are asset rich but cash poor and want to cover healthcare, caregiving or family needs without selling 
  • Business owners and investors who need capital for a new venture or an opportunity with a short window 
  • Property upgraders bridging the gap between buying a new home and selling the old one 
  • Families planning succession who want to avoid a forced sale that could disrupt the estate plan 

It is not right for everyone. Weigh these before you borrow: 

  • Exit risk: the principal is due at the end of the term. If a sale or refinancing is delayed, you may face extension costs or pressure to sell 
  • Higher rate: the interest rate is typically above bank rates 
  • Fees: arrangement and legal fees apply, so compare total cost, not just the rate 
  • Security: the loan is secured on your property, so default puts the asset at risk 

Seek independent legal and financial advice on your own situation before committing. 

Frequently asked questions 

Q1: What is a bridging loan in Singapore? 

A bridging loan is short-term financing, usually 6 to 24 months, secured against property. It is typically interest-only, and the principal is repaid at the end of the term through a sale, a liquidity event or refinancing.

Q2: Is there an age limit for a bridging loan in Singapore? 

Banks often cap lending by borrower age or reduce the loan tenure for older applicants. Asset-backed private lenders such as GMG assess the property and your exit plan rather than your age. 

Q3: Does a bridging loan need TDSR or income proof? 

Bridging loans from private lenders are assessed on the property value and your repayment plan, so TDSR and income verification are not the basis of approval. All applications remain subject to credit assessment. 

Q4: How much can I borrow against my property? 

Loan-to-value depends on the property type and location. Condos, landed homes, GCBs and shophouses can all qualify, and private lenders often lend at higher LTV than banks. 

Q5: How much does a Singapore bridging loan cost? 

Indicative rates are 5.5% to 7%, depending on LTV and property type, plus arrangement and legal fees. Rates are subject to credit approval. 

Q6: How fast can I get the funds? 

Speed is a core advantage. Approval and funding are typically much faster than a bank mortgage, because the assessment centers on the property rather than full income documentation. 

Q7: Can foreigners get a bridging loan against Singapore property? 

Yes. Singaporeans, PRs and foreigners can apply, subject to credit assessment and the applicable property regulations. 

Next step

Asset rich and want flexibility without selling? Speak to GMG about a Singapore bridging loan against your property. Tell us the property, the amount and your exit plan, and we will come back with indicative terms. [Enquire now] 

Disclaimer: This article is for general information only and is not financial, legal or tax advice, nor an offer or solicitation to enter into any loan. Rates, LTV, fees and terms mentioned are indicative only and subject to change; actual terms depend on the property, borrower and credit assessment, and approval is not guaranteed. Worked examples are illustrative, not a quotation. Manulife and FT Longitude are not affiliated with GMG. Seek independent professional advice before making any borrowing or property decision.

Global Property Bridging Loans: Asset-Based Cash-Out, Faster Than a Conventional Bank Refinance

World map highlighting Singapore, United States, United Kingdom, Thailand, Malaysia, and Australia property markets for cash-out bridging loans

If you own real estate in the US, Singapore, Thailand, Malaysia, the UK, or Australia, and you've held it for several years, there's a strong chance you're sitting on more capital than you realize. The question isn't just whether you can access it. It's how fast, and how certainly. This guide explains why a cash-out bridging loan, not a conventional refinance, is often the right instrument when timing is the priority.

The Problem With a Conventional Cash-Out Refinance

The default move for most owners is a cash-out refinance. It works, eventually. But conventional refinancing runs on bank time: income verification, tax returns, credit history review, committee approval. That process typically takes weeks to months, and it can stall entirely if your income profile doesn't fit a standard debt-servicing model.

For an owner who needs capital to move on a deadline: a new investment, a time-sensitive purchase, a liquidity gap, a multi-month process isn't a minor inconvenience. It's often the difference between closing the opportunity and losing it.

What a Cash-Out Bridging Loan Solves Instead

A cash-out bridging loan is asset-based lending: the loan is underwritten primarily against the property's value, not the borrower's income, tax returns, or credit history. That's precisely what makes it fast.

  • Structured in days, not months — the underwriting bottleneck of a conventional refinance largely disappears when income documentation isn't the gating factor
  • Up to 70–80% loan-to-value, depending on market and property type
  • No personal financials required — no income verification, no tax returns, no employment letters
  • In Singapore: no TDSR. Because the loan is asset-based rather than income-based, Singapore's Total Debt Servicing Ratio framework doesn't apply the way it does to a conventional home loan
  • No age limit in Singapore as well — a criterion that disqualifies many owners, particularly retirees, from traditional bank refinancing

Bridging Loan or Refinance: How to Decide

These aren't competing versions of the same product — they solve different problems:

  • A refinance may offer a marginally lower rate over a longer term, if your income profile qualifies and you have months to wait.
  • A bridging loan trades a modest rate premium for speed and certainty — the capital (and the deal it's funding) can close before a bank has finished reviewing your file.

For owners moving on a timeline, a purchase with a deadline, a business opportunity, a liquidity need that can't wait, the bridging structure is usually the only one that actually fits the situation, independent of rate.

Why Property Owners Are Sitting on Untapped Equity

Two trends make this a meaningfully underused opportunity right now:

1. Long holding periods with no refinance activity. Many owners bought property years ago, for a child attending university abroad, as a long-term investment, or as a second home, and never revisited the financing.

2. Substantial price growth across major markets. Values in Singapore, the US, the UK, Thailand, Malaysia, and Australia have climbed significantly over the past 5–10 years in most segments. The gap between purchase price and current value is often far larger than owners have calculated, and because the loan is asset-based, that entire gap is potentially accessible regardless of income profile or how quickly it's needed.

Available Across Six Markets

  • Singapore — asset-based lending structured outside the TDSR framework
  • United States — cash-out bridging for foreign nationals and expats who wouldn't qualify under conventional US bank criteria
  • United Kingdom — fast equity release against UK residential and buy-to-let property held by non-resident owners
  • Thailand — financing structured around foreign ownership restrictions on land and condominium title
  • Malaysia — asset-based lending for both resident and non-resident owners
  • Australia — cash-out bridging for offshore owners of Australian residential and investment property

Who This Is Actually Built For

  • Owners on a deadline — a purchase, investment, or opportunity that can't wait for a conventional bank timeline
  • Retirees and older owners who don't fit standard age-based lending criteria
  • Business owners and investors whose income is complex, offshore, or doesn't fit a conventional debt-servicing model
  • Long-term overseas property holders who bought years ago and never refinanced
  • Expat and globally mobile families with real estate spread across two or more countries

A Note for Private Banks, Wealth Managers, and Relationship Managers

This is a scenario many relationship managers encounter but can't always resolve internally: a client who needs to move faster than the institution's standard process allows, or whose income profile doesn't fit the credit box. Referring that need to a specialist bridging lender doesn't mean losing the client, it means solving a problem they've likely already started shopping around for elsewhere, while the broader relationship stays with you.

Frequently Asked Questions

Q1: What's the actual difference between a bridging loan and a cash-out refinance?

A refinance is underwritten around income, credit history, and a longer approval timeline. A bridging loan is underwritten primarily against the property's value, which is what allows it to close in days rather than months.

Q2: Do I need to show income or personal financials to qualify? 

No. This type of financing is underwritten primarily against the property's value, not the borrower's income, tax returns, or employment history.

Q3: Does Singapore's TDSR apply to this type of loan? 

No. Because the loan is asset-based rather than income-based, it typically sits outside the Total Debt Servicing Ratio framework that applies to conventional home loans in Singapore.

Q4: Is there an age limit to qualify? 

No, one of the main reasons retirees and older property owners use asset-based bridging finance instead of a conventional bank refinance.

Q5: How much of my property's value can I borrow against? 

Typically up to 70–80% loan-to-value, depending on the market, property type, and lender's terms.

Q6: Is a bridging loan more expensive than a refinance? 

Often carries a modest rate premium in exchange for speed and certainty, the trade-off is typically worthwhile when timing, not rate, is the deciding factor.

Q7: Can I do this if I'm not a citizen or resident of the country where the property is located?

Yes. Cross-border, asset-based lending is specifically structured for foreign nationals, expats, and non-resident owners.

Next Steps

Every market and every property is different, loan-to-value limits and structuring vary by country. The first step is understanding what's actually available, and how fast it can move.

Have equity tied up in property and need to access it quickly? Start with a conversation about what your property can support.

Donald Klip, Co-Founder — Global Mortgage Group

[email protected] | +65 9773 0273 | www.gmg.asia

Asset-Rich, Cash-Poor in Singapore? How a Cash-Out Bridging Loan Unlocks Your Property Equity — Fast

Singapore property representing equity unlocked through a cash-out bridging loan

Singapore property values have never been higher. For many owners, that's created a strange problem: significant wealth locked inside a home or investment property, with no easy way to access it without selling. This is the "asset-rich, cash-poor" position, and it's more common among high-net-worth Singapore property owners than most people realise.

A cash-out bridging loan is one of the fastest ways to solve it.

What Is a Cash-Out Bridging Loan?

A cash-out bridging loan is a short-term loan secured against property you already own, which releases a portion of your equity as cash, without requiring you to sell the property. Unlike a traditional refinance, bridging finance is built for speed and flexibility, funding in days or weeks rather than the months a bank refinance typically takes.

In Singapore, cash-out bridging loans are used by property owners to unlock liquidity for a business opportunity, an investment, an overseas property purchase, a family need, or simply to convert illiquid equity into working capital, all without triggering a sale.

The Asset-Rich, Cash-Poor Problem in Singapore

It's a familiar pattern: a property purchased years ago has appreciated substantially, but the owner's liquid cash position hasn't kept pace. When an opportunity or need for capital arises, the options are limited:

  • Sell the property — triggering transaction costs, taxes, and the loss of a long-term asset
  • Apply for a traditional bank refinance — slow, and often constrained by TDSR (Total Debt Servicing Ratio) rules that cap how much can be borrowed against income, not asset value
  • Do nothing — and leave the equity idle

A cash-out bridging loan sidesteps all three.

Key Features of GMG's Cash-Out Bridging Loans

FeatureDetail
Loan-to-value (LTV)Up to 80% — among the highest available for this type of lending in Singapore
TDSR requirementNone — approval is based on the asset, not income-servicing ratio
Age restrictionNone — assessed on the property, not the borrower's age
RateLowest globally for this type of asset-backed loan
Funding speedDays to weeks, versus months for a typical bank refinance

Who Uses a Cash-Out Bridging Loan?

  • Business owners needing capital for an acquisition, expansion, or working capital, without waiting on slow bank approval cycles
  • Investors wanting to redeploy Singapore property equity into other assets, including overseas property, private credit, or other investment opportunities
  • Families funding a major expense: education, an overseas property purchase, or another significant outlay, without liquidating long-held assets
  • Owners bridging a timing gap, such as buying a new property before the sale of an existing one completes

How the Process Works

  1. Valuation — the property is assessed to determine current market value and available equity
  2. Structuring — loan size, term, and LTV are structured around the borrower's specific need
  3. Approval — because assessment is asset-based rather than income-based, approval is typically faster and more certain than a conventional bank application
  4. Funding — capital is disbursed, often within days of final approval

Frequently Asked Questions

Q1: What is the maximum loan-to-value (LTV) for a cash-out bridging loan in Singapore? 

Up to 80% LTV is available, depending on the property and borrower profile, significantly higher than many conventional refinancing options.

Q2: Do I need to meet TDSR requirements for a cash-out bridging loan?

No. Cash-out bridging loans are assessed against the value of the asset, not the borrower's income-servicing ratio, so TDSR does not apply.

Q3: Is there an age limit to qualify?

No. Unlike many bank lending products, there is no age restriction on cash-out bridging loans.

Q4: How fast can a cash-out bridging loan fund?

Bridging loans are structured for speed, funding can typically be arranged in days to weeks, compared to the months a traditional bank refinance can take.

Q5: What can the funds be used for?

There are generally no restrictions, funds can be used for business capital, investment, overseas property purchases, family expenses, or any other personal or commercial purpose.

California’s AI Boom Is Building Home Equity Fast. Here’s How to Put It to Work Without Selling.

California homeowners viewing a luxury Bay Area property with the San Francisco skyline and Golden Gate Bridge in the background.

Every technology cycle that has occurred has had an effect on Silicon Valley real estate. There has been a change in housing demand during the dot-com cycle. Social media also led to a change in housing demand. With the rise in platform companies in the 2010s, there have been more changes. There are currently effects of the AI technology investment cycle on local markets. Stock awards and tenders are driving housing demand. Future IPOs might also affect some areas.

Homeowners in California might have accumulated considerable home equity through their period of owning the house. If there is any rise in the value of the property, it will make the home equity increase even more. However, this home equity might not be utilized at all. The important thing is how to make use of this quickly. Some homeowners would like to finance a new property or other businesses.

This is where the bridge loan comes into play.

California homeowners viewing a luxury Bay Area property with the San Francisco skyline and Golden Gate Bridge in the background.

The AI Boom Has Turned Home Equity Into a Bay Area Talking Point

These numbers cannot be ignored with respect to the recent increases. The median price of houses sold in San Francisco has risen to over $2 million. Experts attribute the rise to hiring of personnel in AI and corresponding financial benefits. In Santa Clara County, there have been several transactions in the luxury real estate segment. Transactions in the range of $5 million and above have increased considerably.

The trends of the down payment have followed a similar trajectory. The down payment among the wealthy Bay Area home buyers has increased from 28% prior to 2023 to around 35%. According to Realtor.com, there are indications that the cause of this trend is sales from stocks and other such liquidity events. These can be used by the buyer instead of financing for a bigger portion. Economists from Redfin have called this a “K-Shaped” housing market. The AI wealth is helping boost prices in some areas.

This is not just limited to high-end properties. According to PwC and Urban Land Institute, San Jose and San Francisco are rising markets. Their rankings in 2026 highlight the broader trends in the real estate market of that region. The impact of wealth driven by artificial intelligence seems to be extending.

The nationwide figure shows the extent of the rise in home equity. In Q2 2026, the mortgage holder equity across the United States stood at a record high of $18 trillion. This information was provided by ICE Mortgage Technology in its Mortgage Monitor report. The tappable equity is currently $11.7 trillion. This refers to the level of equity held prior to attaining the 80% loan-to-value ratio. The average equity across the U.S. stands at approximately $212,000 for each mortgaged household. California boasts some of the most expensive homes in the U.S. Additionally, it receives some of the best investments in AI technology.

California homeowners in AI markets may have built up a lot of home equity over the years. Home equity may constitute one of their biggest personal wealths. However, much of this home equity may be underutilized.

Why a Bridge Loan — Not a Sale — Is the Right Tool to Access It

Usually, homeowners have three alternatives to access their accumulated equity. They may either sell their property, refinance their home, or obtain a secondary position loan. The sale will put an end to their ownership of the property. In refinancing, there is the replacement of the current mortgage. A secondary position loan gives the borrower an opportunity to borrow from his equity without taking out another mortgage.

Selling involves relinquishing an asset that may keep increasing in value. In addition to transaction costs, selling involves paying more money for the next purchase. Cash-out refinance involves refinancing the whole first mortgage. This is likely to lead to an increase in the interest rates.

The bridge loan does not suffer from either problem. It operates in tandem with your current mortgage. It is normally a temporary, interest-only loan. Term lengths typically last between six months and two years. The loan is dependent on the current value of the property. This allows those seeking a bridge loan to:

  • Make quick moves on the new purchase: Put home equity to work in the next down payment or offer.
  • Hold onto your low mortgage: Take advantage of equity that you have without having to refinance out of an existing first mortgage at higher rates.
  • Reuse your money: Invest in private business or real estate without selling anything first.
  • Fund temporary expenses: Pay for remodeling, taxes, or cash flow requirements pending a future liquidity event.

Bridge loans usually depend on the value of the property being used for collateral and any equity available. Bridge loans usually need less paperwork to do with income than other types of refinancing loans. This means that they take less time to close.

Turning AI-Boom Equity Into a New Investment, Not Just a Bigger House

Homeowners may not be interested in having an even bigger home. Rather, they see their home equity as investible capital. This would enable them to diversify their investment portfolio, which may otherwise be concentrated in one single investment.

This is because:

  • The second criterion: Purchase a rental property or enter a new market before you sell your present house.
  • Private markets: Invest in private credit and private market options with fixed investment timeframes.
  • Capital for business: Raise capital to start a new venture, make an investment in a partnership, or raise working capital without selling any existing investments.
  • Diversification: Use the equity from your present home to diversify into other investments.

The biggest advantage here would be convenience and flexibility. A bridge loan transforms your trapped property equity into usable capital. This way, you will be able to take quick action when necessary without having to sell your property or substitute your current mortgage.

What to Weigh Before You Borrow

A bridge loan provides temporary finance, although it is usually more expensive than traditional mortgages. Not all situations will be suitable for taking out such loans. In order to proceed, one needs to take into consideration the following points.

  • Exit strategy: Create an exit plan to pay off the bridge loan well before it expires. Methods include selling, refinancing, or using other sources of money.
  • Combined loan-to-value ratio: The lender factors in your current mortgage when measuring your leverage. This will determine your equity position.
  • Cost versus opportunity: Bridge loans come at higher rates than traditional mortgages. Weigh both the costs and opportunities that it presents.
  • Market conditions: The California market has been witnessing fast appreciation in the AI niche. Consider slow appreciation when analyzing your investment plan.

Frequently Asked Questions

Q1: Is home equity in California actually higher because of the AI boom? 

In AI-led markets like San Francisco and Santa Clara County, there has been a huge increase in the price of homes. The financial gain from AI has fueled demand for housing. This has been noted in reports by Redfin, Compass, and others through 2026.

Q2: What's the difference between a bridge loan and a cash-out refinance? 

Cash-out refinancing means replacing your current mortgage with a bigger one. The drawback is that you will lose your lower interest rate. Bridge financing is different from cash-out financing in the way that bridge financing is a totally new loan.

Q3: How fast can a bridge loan close? 

Bridge loans are primarily based on the worth of the property and equity. They may not require much information on income when compared to the traditional mortgage. Hence, bridge loans close fast. Most transactions can be completed in a matter of weeks, while the traditional mortgage takes 30-45 days or more.

Q4: Can bridge loan proceeds be used for something other than buying another home? 

Yes, the money from a bridge loan is often flexible once it has been disbursed. In many cases, homeowners will invest the money in purchasing other real estate properties. Some people choose to invest their money in private markets and even private companies.

Q5: Is a bridge loan risky if California home prices moderate? 

All loans that are priced on the basis of asset value are at risk of fluctuating prices. Always borrow conservatively in relation to the total loan-to-value ratio. Moreover, always develop an exit strategy prior to the expiry of the loan period.

Private Credit Financing in Asia Pacific: How It Works and Who It’s For

Private credit financing for middle-market companies in Asia Pacific

Private credit is financing structured against a company's assets, cash flow, or a combination of both, rather than underwritten purely on a borrower's credit rating like a conventional bank loan. In Asia Pacific, it has become a primary source of growth and bridge capital for middle-market companies, particularly in Thailand, Malaysia, Singapore, and Indonesia, as regional banks tighten lending criteria.

What Is Private Credit?

Private credit is non-bank lending provided by asset managers, family offices, and specialist financing firms rather than commercial banks. Unlike a standard bank loan, which is underwritten mainly on the borrower's credit profile and financial ratios, private credit is structured against a defined collateral pool.

That collateral pool can include:

  • Hard assets — real estate, equipment, inventory, or other tangible collateral
  • Cash flow waterfalls — structured claims on a company's net operating income
  • Additional credit enhancements — guarantees, subordination structures, or covenants tailored to the deal

This asset- and structure-based approach is what allows private credit to finance transactions that don't fit inside a bank's standard credit box, including bridge financing, growth capital, and special situations.

Why Private Credit Is Growing in Asia Pacific

Banks across Asia Pacific have been tightening general lending, particularly for mid-sized companies with financing needs that fall outside standardized credit products. As that gap has widened, private credit has stepped in as an alternative source of capital for companies that have strong underlying businesses but don't fit conventional bank criteria, whether due to deal complexity, timeline, or structure.

This shift mirrors a broader global trend: as regulatory capital requirements make certain categories of lending less attractive for banks, private credit managers have absorbed a growing share of corporate financing, a pattern playing out across both developed and emerging markets, including Asia Pacific.

How Private Credit Financing Is Structured

Every private credit transaction is structured around the specific asset base and cash flow profile of the borrower. Common structures include:

  1. Bridge financing — short-term capital secured against real assets, used to fund a transaction ahead of permanent financing or a liquidity event
  2. Growth capital — financing tied to a company's expansion plans, often secured against a blend of assets and projected cash flow
  3. Special situations financing — capital for complex, time-sensitive, or non-standard scenarios that don't fit conventional lending categories

Deal sizes in this space typically range from US$10 million to US$100 million, reflecting the middle-market companies most affected by the retreat of conventional bank lending.

Private Credit Financing by Market

GMG Capital Advisory, the private credit and special situations arm of Global Mortgage Group (GMG), is currently most active in Thailand, Malaysia, Singapore, and Indonesia. Each market has distinct dynamics driving demand.

Private Credit Financing in Thailand

Thailand is currently one of GMG Capital Advisory's busiest markets for private credit. Demand is concentrated among mid-sized companies pursuing growth, acquisitions, or bridge capital ahead of a transaction, where conventional Thai bank lending criteria don't fit the timeline or structure required.

Private Credit Financing in Malaysia

In Malaysia, private credit has become an increasingly common solution for business owners and middle-market companies whose financing needs, often tied to expansion or restructuring, fall outside standard bank products.

Private Credit Financing in Singapore

As a regional financial hub, Singapore sees demand for private credit both from local companies and from cross-border transactions structured through Singapore-based holding entities, where speed and structuring flexibility matter as much as pricing.

Private Credit Financing in Indonesia

Indonesia's private credit activity is driven largely by growth-stage companies and special situations financing, where deal complexity or timeline puts transactions outside what conventional Indonesian bank lending can accommodate.

Who Private Credit Financing Is For

Private credit financing through GMG Capital Advisory is typically used by:

  • Middle-market companies with a financing need that doesn't fit standard bank criteria
  • Business owners pursuing a transaction, expansion, or restructuring on a timeline banks can't accommodate
  • Private banks and client advisors whose clients need a financing solution outside the bank's own product shelf

GMG Capital Advisory works alongside, not in competition with, private banks, arranging financing from third-party capital providers that solves the client's need while the bank retains the underlying relationship.

Key Terms Glossary

Private credit

Non-bank lending structured against a company's assets or cash flow rather than credit rating alone.

Special situations financing

Capital for complex, time-sensitive, or non-standard transactions outside conventional lending categories.

Bridge financing

Short-term capital secured against assets, used to fund a transaction ahead of permanent financing.

Middle-market company

A business generally too large for small-business lending but below the scale that accesses large-cap institutional debt markets.

Collateral pool

The combined set of assets, cash flows, and credit enhancements securing a private credit facility.

FAQ

Q1: What is private credit financing?

Private credit financing is capital provided by non-bank lenders, structured against a company's assets, cash flow, or both, rather than underwritten purely on credit rating the way a conventional bank loan is.

Q2: How is private credit different from a bank loan?

A bank loan is underwritten primarily on a borrower's credit profile and standardized ratios. Private credit is structured around a specific collateral pool: hard assets, cash flow waterfalls, and other credit enhancements, making it more flexible for deals that don't fit a bank's criteria.

Q3: What deal sizes does GMG Capital Advisory arrange?

GMG Capital Advisory typically arranges private credit and special situations financing between US$10 million and US$100 million for middle-market companies across Asia Pacific, connecting borrowers with institutional and private capital providers.

Q4: Which markets is GMG Capital Advisory most active in?

GMG Capital Advisory's busiest markets are currently Thailand, Malaysia, Singapore, and Indonesia.

Q5: Why is private credit growing in Asia Pacific?

As banks across the region tighten general lending, private credit has become an increasingly important source of growth and bridge capital for companies whose financing needs fall outside conventional bank products.

Q6: Is private credit financing more expensive than a bank loan?

Private credit is generally priced to reflect its flexibility and speed relative to conventional bank lending. Exact terms depend on the collateral structure, deal complexity, and timeline of each transaction.

Q7: How long does it take to close a private credit transaction?

Timelines vary by deal complexity and collateral structure, but a key advantage of private credit over conventional bank lending is the ability to move faster on transactions with defined timelines.

Q8: Who is eligible for private credit financing?

Eligibility is based primarily on the strength of the underlying collateral pool and cash flow rather than a standardized credit score, which is why companies with strong assets but a non-standard financing need often qualify even when a bank has declined them.

Unlocked in UK: Assessing Any UK Off-Plan Scheme Marketed Overseas — A Buyer’s Framework

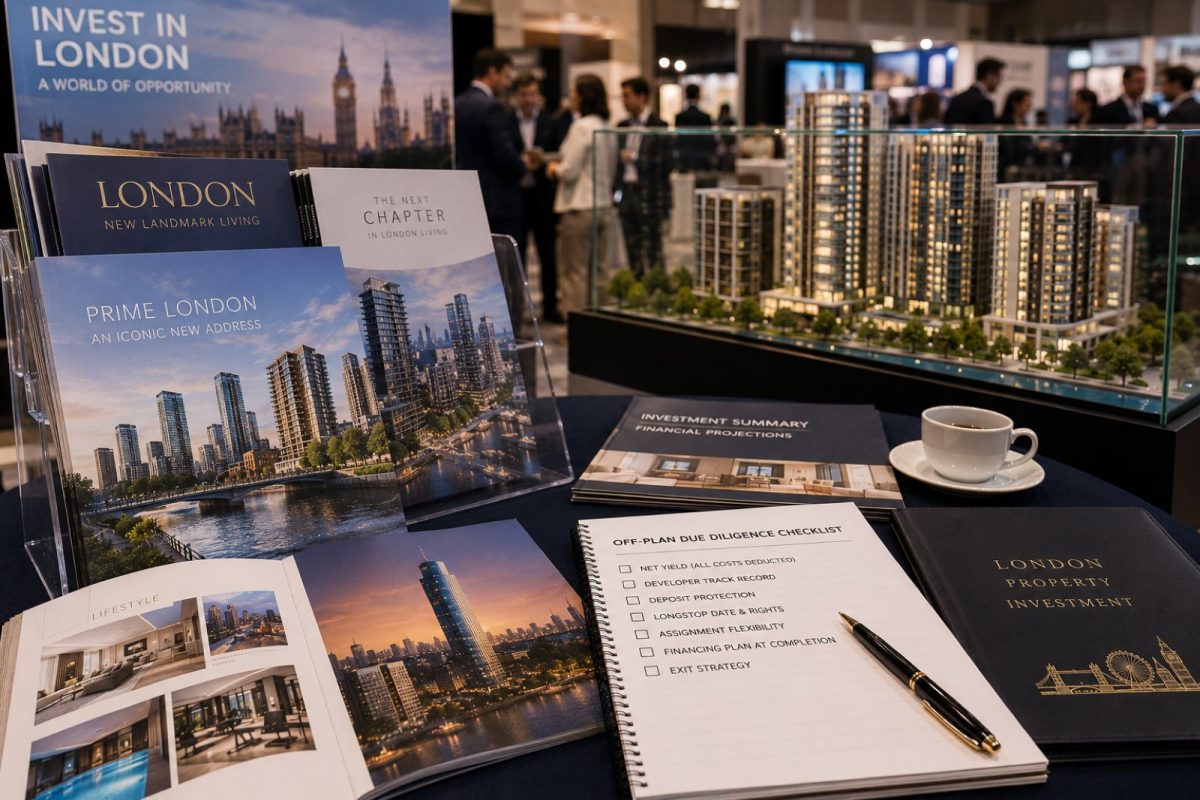
Overseas property exhibition brochures for a UK off-plan scheme, representing a buyer's framework for assessing off-plan developments

UK developments are marketed intensively across Singapore, Hong Kong, Kuala Lumpur, Dubai and beyond, typically through exhibition weekends, agent networks and glossy projections. Some of these schemes are excellent. Some are not. The difficulty for an overseas buyer is that the marketing presentation looks broadly identical either way, and the buyer is usually being asked to commit before they have seen the site, the area, or in many cases the country.

Speak to GMG about releasing equity from your UK property. Donald Klip, Co-Founder — Global Mortgage Group.

[email protected] | +65 9773 0273 | www.gmg.asia

This closing guide in the development series is deliberately generic, because the framework matters more than any individual scheme. These are the questions worth asking about any UK off-plan development marketed to you overseas, whatever the name on the brochure.

Interrogate the Projection, Not the Brochure

Rental yield projections in overseas marketing material are projections, not commitments, and they are frequently gross rather than net. A gross yield that ignores service charge, ground rent, management fees, void periods, and UK tax under the Non-Resident Landlord Scheme is not a number an investor can actually plan around. Ask for the net figure, with every deduction itemised, and treat reluctance to provide it as informative in itself.

Similarly, capital appreciation projections presented as though they were a forecast deserve scrutiny. Prime central London has spent over a decade below its 2014 peak, as this series has documented throughout. Any projection implying steady upward appreciation should be tested against that actual, recent, well-evidenced history.

"The question I would ask any agent selling a UK scheme at a Singapore or Dubai exhibition is simple: show me the net yield after service charge, ground rent, voids and UK tax, and show me your comparable evidence for the capital projection. Reluctance to answer either question tells you everything you need."
- Donald Klip, Co-Founder — Global Mortgage Group

The Questions That Actually Determine the Outcome

Beyond the numbers, the structural questions matter more than buyers realise. Is the developer established with a delivery record, or is this their first major scheme? Is the deposit protected, and under what mechanism? What is the contractual longstop date, and what are the buyer's rights if delivery slips past it? Is there any restriction on assigning the contract before completion, should circumstances change during the build period?

And critically, the financing question this series returns to repeatedly: what happens at completion if the mortgage that was assumed at exchange is not available, or the valuation comes in below the contracted price? A buyer who has thought that scenario through before exchanging, and pre-arranged a bridging contingency, is in an entirely different position from one who first considers it when the completion notice arrives.

Questions to Ask Before Exchanging on Any Overseas-Marketed UK Scheme

  • What is the net yield after service charge, ground rent, voids and UK tax, itemised
  • What is the developer's delivery record, and how is my deposit protected
  • What is the longstop date, and what are my rights if delivery slips beyond it
  • Can I assign the contract before completion if my circumstances change
  • What is my plan if the completion mortgage falls short or the valuation comes in low

About Global Mortgage Group

Global Mortgage Group (GMG) is a Singapore-headquartered cross-border real estate finance firm operating across 23+ jurisdictions, specialising in equity release, bridging loans and structured property finance for international property owners. GMG works with private clients, family offices and their advisers to unlock capital held in prime residential real estate.

Donald Klip, Co-Founder — Global Mortgage Group

[email protected] | +65 9773 0273 | www.gmg.asia

This is the final article in the Development guide section of GMG's Unlocked in the UK series. Speak to Donald Klip and the GMG team before exchanging on any UK off-plan purchase.

Unlocked in UK: White City, Old Oak and Outer Regeneration — Financing the Growth-Story Purchase

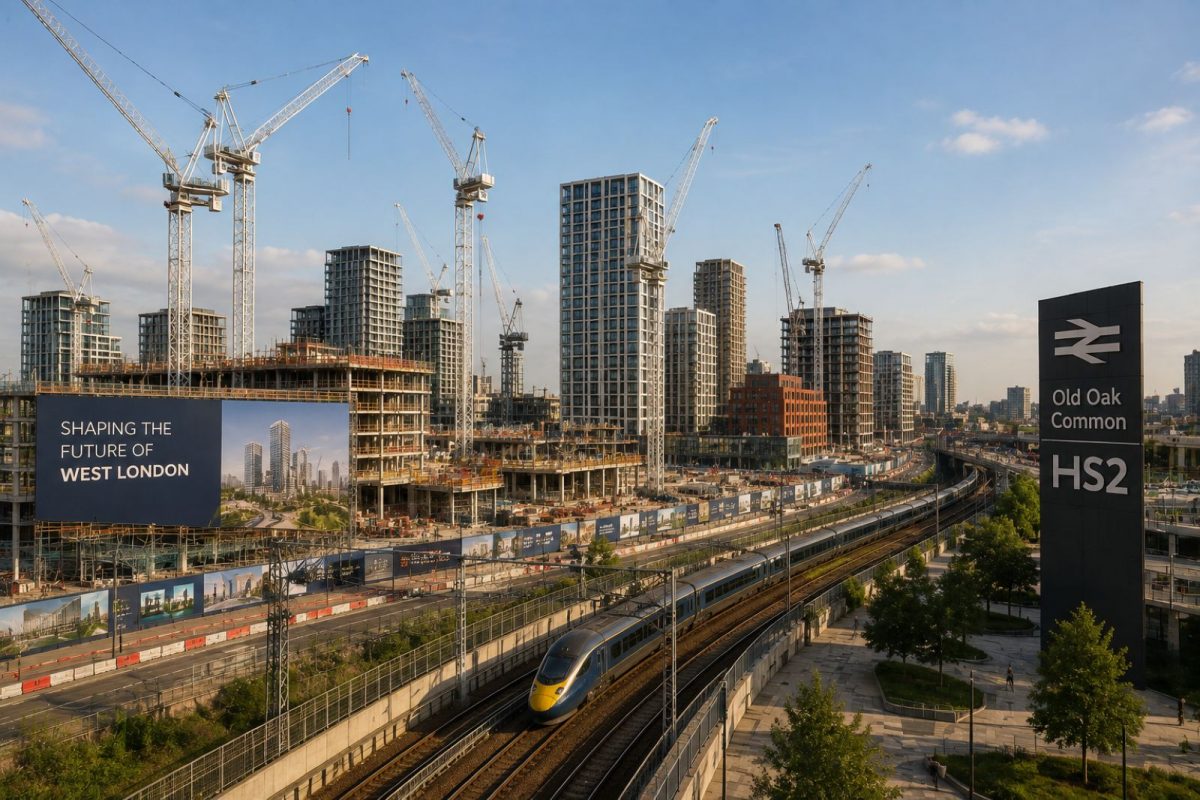
Old Oak Common construction site near HS2, representing outer-London regeneration financing for growth-story property purchases

White City, Old Oak Common and comparable outer-London regeneration zones are marketed to overseas investors on a fundamentally different basis from prime central London, in some ways echoing the marketing approach seen at Battersea Power Station. The pitch is not established prestige or scarcity; it is future growth, transport infrastructure arriving, employment moving in, an area transitioning over a ten to fifteen year horizon. Old Oak's HS2 interchange and White City's media and university cluster are the anchors of that story.

Speak to GMG about releasing equity from your UK property. Donald Klip, Co-Founder — Global Mortgage Group.

[email protected] | +65 9773 0273 | www.gmg.asia

For a patient investor, the logic is sound and the entry price is a fraction of prime central London. But growth-story purchases carry financing characteristics that differ meaningfully from buying an established asset, and international buyers marketed these schemes overseas frequently do not have those differences explained to them clearly.

Lending Against a Future, Not a Present

A lender does not lend against the regeneration story. It lends against the property's value today, in the area as it exists today, with today's comparable evidence. This is the central tension in a growth-story purchase: the buyer is paying partly for a future that has not arrived, while the lender is valuing a present that may not yet support that price.

Where infrastructure timelines slip, and major infrastructure timelines frequently do, the gap between the price paid and the value a lender will recognise can persist for years longer than the buyer anticipated. That has direct consequences at refinancing, when a facility matures and the valuation has not caught up with the purchase price, a dynamic explored further in this series' Nine Elms guide.

"The growth story might well be right. Some of these areas will transform, and the early buyers will do very well. But the lender is not underwriting the story, and the buyer needs to have the capital to hold the position long enough for the story to actually arrive. Those are two different bets and buyers routinely conflate them."
- Donald Klip, Co-Founder — Global Mortgage Group

Holding Power Is the Real Question

The practical question for a growth-story buyer is therefore not whether the area will improve, but whether they can hold the asset comfortably through the period before it does. That means financing structured for a long hold, realistic assumptions about rental income during the transition, and enough headroom to absorb a refinancing where the valuation has not moved as hoped.

Buyers who financed on the assumption of rapid appreciation, and who need that appreciation to refinance, are exposed in a way that buyers with genuine holding power are not. This is the distinction that matters most in this segment, and it is rarely the one the overseas marketing addresses.

Growth-Story Purchase Considerations

  • Lenders value the area as it is today, not as the regeneration marketing describes it
  • Infrastructure timelines slip; model a longer hold than the sales projection assumes
  • Structure financing for holding power, not for an assumed rapid appreciation
  • Model rental income realistically for the transition period, not the mature-area projection

About Global Mortgage Group

Global Mortgage Group (GMG) is a Singapore-headquartered cross-border real estate finance firm operating across 23+ jurisdictions, specialising in equity release, bridging loans and structured property finance for international property owners. GMG works with private clients, family offices and their advisers to unlock capital held in prime residential real estate.

Donald Klip, Co-Founder — Global Mortgage Group

[email protected] | +65 9773 0273 | www.gmg.asia

This is part of GMG's Unlocked in the UK development guide series. The final development guide covers how to assess any off-plan scheme marketed overseas.