Unlocked in UK: Chelsea Barracks and Ultra-Prime New Build — Financing at the Top of the Market

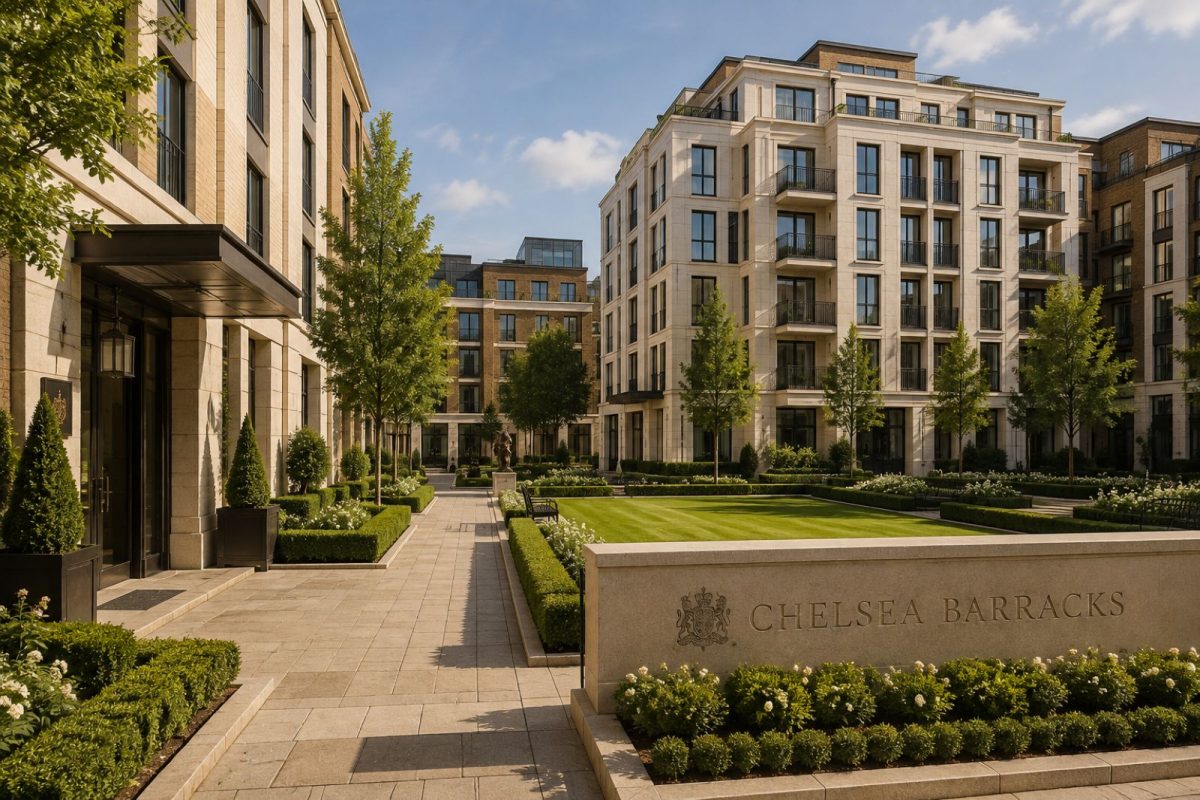
Chelsea Barracks low-density development, representing ultra-prime new-build financing for principal residences and family assets

Chelsea Barracks sits at the opposite end of the new-build spectrum from the high-density towers of Nine Elms. Developed on one of the largest single sites ever released in prime central London, and backed by Qatari investment, it represents the ultra-prime end of new-build delivery: low density, high specification, and priced accordingly.

Speak to GMG about releasing equity from your UK property. Donald Klip, Co-Founder — Global Mortgage Group.

[email protected] | +65 9773 0273 | www.gmg.asia

Buyers here overlap substantially with the family office, trust and GCC purchaser profiles covered elsewhere in this series. This is not, in the main, a buy-to-let investor market. It is a market of principal residences, pieds-à-terre and long-hold family assets, frequently acquired through structures rather than in personal names.

Why Ultra-Prime New Build Finances Differently

At this price point, conventional mortgage products are largely irrelevant. Facilities are structured privately, sized against the purchaser's global balance sheet rather than a standard income multiple, and negotiated rather than selected from a product range. The relevant question is rarely whether a buyer qualifies in the conventional sense, but how a facility should be structured around an existing international wealth position, the ownership vehicle, and the family's broader leverage strategy.

"At this level nobody is filling in a mortgage application. The conversation is about how a facility fits alongside everything else the family already holds, in every jurisdiction they hold it, and which structure the property is going into. The property is the easy part."
- Donald Klip, Co-Founder — Global Mortgage Group

Structuring, and the Sharia-Compliant Dimension

Given the buyer profile, a meaningful share of transactions in this segment involve trust or corporate ownership vehicles, and for some Gulf families, a preference for Sharia-compliant financing structures rather than conventional interest-bearing debt, as covered in this series' GCC buyer guide. Both requirements are entirely standard at this end of the market, but both narrow the lender field considerably, and neither is well served by mainstream UK lending.

Buyers should also note that the conservation, heritage and covenant considerations discussed in this series' Mayfair guide apply in modified form to major prime central London new-build schemes, where estate management arrangements and long-term covenants can affect future alterations, letting and resale.

Ultra-Prime New-Build Financing Considerations

  • Facilities are privately structured against global wealth, not selected from a standard product range
  • Trust and corporate ownership vehicles are the norm rather than the exception
  • Sharia-compliant structuring is a genuine requirement for a meaningful share of buyers
  • Estate covenants and management arrangements can affect alterations, letting and resale

About Global Mortgage Group

Global Mortgage Group (GMG) is a Singapore-headquartered cross-border real estate finance firm operating across 23+ jurisdictions, specialising in equity release, bridging loans and structured property finance for international property owners. GMG works with private clients, family offices and their advisers to unlock capital held in prime residential real estate.

Donald Klip, Co-Founder — Global Mortgage Group

[email protected] | +65 9773 0273 | www.gmg.asia

This is part of GMG's Unlocked in the UK development guide series. The next guide covers branded residences.
Unlocked in UK: Nine Elms and the Vauxhall Corridor — Financing in a High-Supply New-Build Market

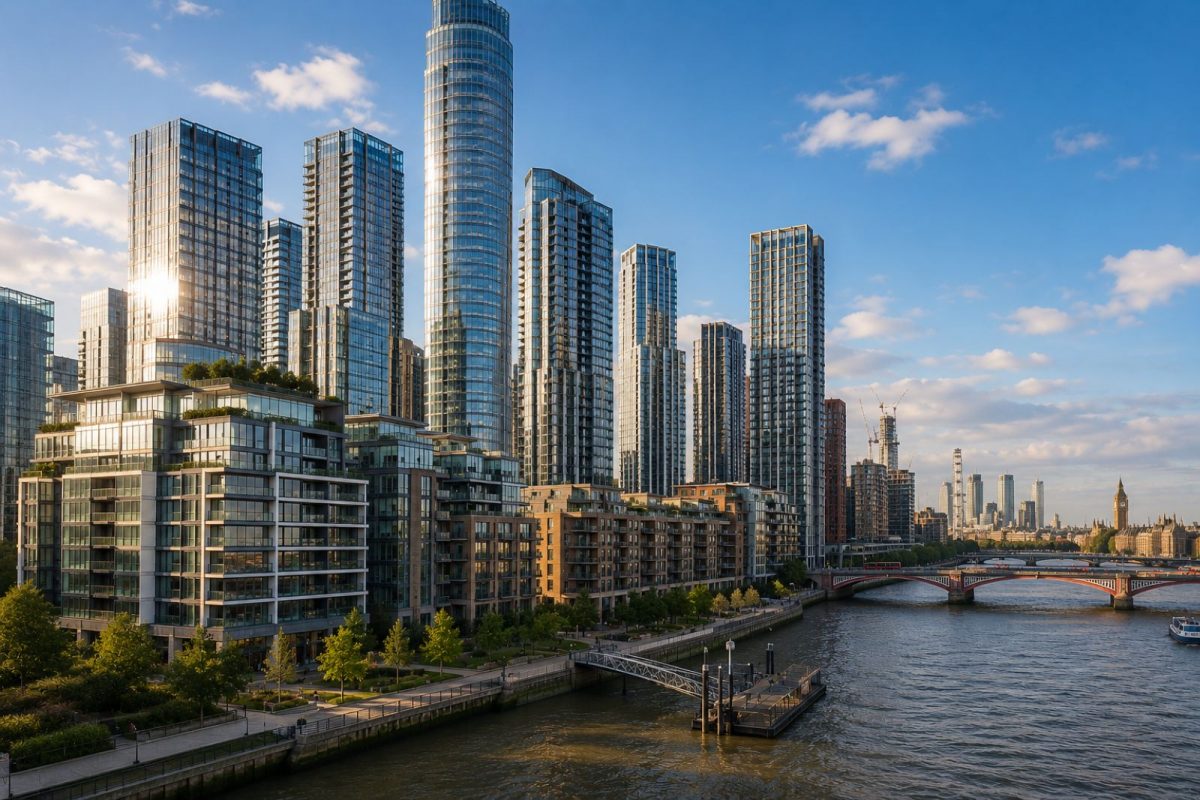
Nine Elms and Vauxhall riverside towers, representing high-supply new-build financing considerations for overseas investors

The Nine Elms and Vauxhall regeneration corridor, stretching along the south bank between Battersea and Lambeth and anchored by the US Embassy relocation, represents one of the highest-density new-build delivery zones anywhere in London. Multiple towers from multiple developers have completed across a compressed period, and the area was marketed extensively to overseas investors throughout its delivery.

Speak to GMG about releasing equity from your UK property. Donald Klip, Co-Founder — Global Mortgage Group.

[email protected] | +65 9773 0273 | www.gmg.asia

This concentration of supply is the defining financing characteristic of the area, and it cuts both ways. For buyers, it has meant genuine choice and negotiating room. For owners looking to refinance or exit, it means competing against a large number of directly comparable units, which affects both valuation and the speed of any sale.

Why High Supply Affects Financing, Not Just Price

Lenders assess new-build apartments partly on how readily the unit could be sold if they ever needed to enforce their security. In an area where hundreds of broadly similar units may be available at any given time, that assessment is less favourable than for a scarce period property in an established postcode, and some lenders apply tighter loan-to-value limits or reduced appetite as a result.

"Supply concentration is the thing overseas investors most consistently underestimate about this part of the market. It affects your entry price, which buyers notice, and it affects your lender's appetite and your exit liquidity, which they usually do not notice until they need to refinance."
- Donald Klip, Co-Founder — Global Mortgage Group

Refinancing an Existing Nine Elms Holding

For investors who bought during the area's marketing push and now hold completed units, refinancing conversations tend to centre on two things: whether the current valuation supports the loan amount required, and whether the rental income the unit generates is sufficient for a buy-to-let assessment in the current rate environment. Owners holding multiple units across the corridor should consider the portfolio-level refinancing approach discussed elsewhere in this series rather than treating each unit as a separate application.

Where a valuation has not performed as originally hoped, an owner facing a maturing facility has a genuine strategic decision rather than a purely administrative one: inject capital to refinance at a lower loan-to-value, sell into a competitive market, or restructure. That decision benefits from being made deliberately and early, rather than in the final weeks before a facility expires, a discipline that applies as much to UK property investors generally as it does to owners specifically in this corridor.

Nine Elms and Vauxhall Financing Considerations

  • High comparable supply affects lender appetite and exit liquidity, not just the entry price
  • Some lenders apply exposure limits restricting units financed within a single scheme
  • Owners of multiple units should explore portfolio-level refinancing rather than unit-by-unit renewal
  • Address maturing facilities early, particularly where valuations have not performed as expected

About Global Mortgage Group

Global Mortgage Group (GMG) is a Singapore-headquartered cross-border real estate finance firm operating across 23+ jurisdictions, specialising in equity release, bridging loans and structured property finance for international property owners. GMG works with private clients, family offices and their advisers to unlock capital held in prime residential real estate.

Donald Klip, Co-Founder — Global Mortgage Group

[email protected] | +65 9773 0273 | www.gmg.asia

This is part of GMG's Unlocked in the UK development guide series. The next guide covers Chelsea Barracks and the ultra-prime new-build segment.

Unlocked in UK: Battersea Power Station — Financing a Purchase in London’s Largest Regeneration Scheme

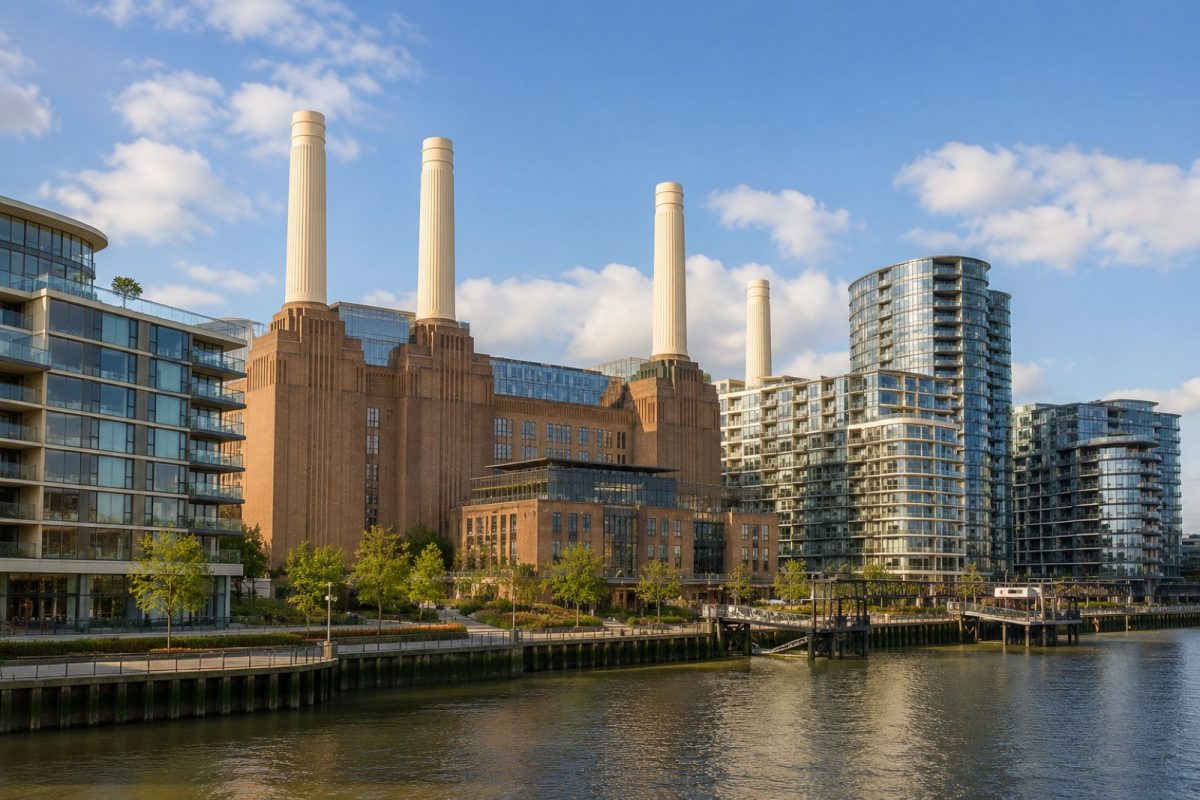
Battersea Power Station development riverside, representing financing considerations for buyers across its phased delivery

Battersea Power Station has become one of the most recognisable names in London property marketing overseas, particularly across Southeast Asia, where the scheme was heavily promoted to Malaysian, Singaporean and Hong Kong investors from its earliest phases onward. For many international buyers, it was their first exposure to UK off-plan investment, and for a significant number it remains the only UK property they own.

Speak to GMG about releasing equity from your UK property. Donald Klip, Co-Founder — Global Mortgage Group.

[email protected] | +65 9773 0273 | www.gmg.asia

The development's scale and phased delivery over more than a decade means buyers across different phases hold very different positions. Someone who exchanged on an early phase years before completion faces an entirely different financing question from a buyer purchasing a completed resale unit today, and the two should not be treated as the same transaction.

The Off-Plan Exchange-to-Completion Gap

The single most consequential financing issue for off-plan buyers at Battersea, and at large phased schemes generally, is the gap between exchange and completion. A buyer who exchanged contracts years ago committed to a price, and paid a deposit, based on their circumstances and the lending environment at that time. By the time the unit is ready and completion is called, their income, their residency status, sterling's exchange rate, and the mortgage market itself may all have shifted materially.

This creates a recurring and genuinely stressful scenario: a buyer contractually committed to complete, facing a developer deadline measured in weeks, discovering that the mortgage they assumed would be available is not, or is available only at a materially lower loan amount than expected. Bridging finance exists precisely for this gap, allowing the buyer to complete on time and then refinance onto a longer-term facility once the immediate deadline has passed.

"The off-plan buyer's problem is that they made a decision years ago and the completion notice arrives against today's lending market. Nobody plans for that gap at the point of exchange, because at exchange it feels a long way off. It never is."
- Donald Klip, Co-Founder — Global Mortgage Group

New-Build Valuation and Lender Appetite

Buyers should also understand that a lender's valuation at completion is an independent assessment, and will not automatically match the price agreed at exchange. Where a valuation comes in below the contracted price, the buyer must fund the shortfall from their own resources, since the lender will advance against the valuation rather than the purchase price. This is a general feature of off-plan purchasing rather than anything specific to this scheme, but it bites hardest at large developments where many units complete in the same window.

Some lenders also apply exposure limits to individual developments, restricting how many units in a single scheme they will lend against. For a buyer at a very large development, this can narrow the available lender pool in ways that are not obvious until an application is already underway.

Questions for a Battersea Power Station Buyer

  • Which phase, and how long between exchange and the expected completion date
  • Has income, residency or currency position changed materially since exchange
  • Is bridging pre-arranged in case the completion mortgage falls short or falls through
  • Has the lender confirmed they have appetite for this specific development

About Global Mortgage Group

Global Mortgage Group (GMG) is a Singapore-headquartered cross-border real estate finance firm operating across 23+ jurisdictions, specialising in equity release, bridging loans and structured property finance for international property owners. GMG works with private clients, family offices and their advisers to unlock capital held in prime residential real estate.

Donald Klip, Co-Founder — Global Mortgage Group

[email protected] | +65 9773 0273 | www.gmg.asia

This is part of GMG's Unlocked in the UK development guide series. The next guide covers Nine Elms and the wider Vauxhall regeneration corridor.

Unlocked in UK: Inheritance Tax-Driven Bridging — Financing a UK Inheritance Tax Liability Without a Forced Sale

Executor reviewing probate documents beside a London property, representing inheritance tax bridging finance for UK property

UK inheritance tax presents a distinctive and often urgent financing challenge for families with UK property, particularly international families and non-doms whose UK-situated assets remain within the scope of UK inheritance tax even where other assets are held outside the UK's tax net. HM Revenue and Customs generally expects inheritance tax to be paid within six months of death, well before the probate process required to sell a property or access other estate assets is typically complete.

Speak to GMG about releasing equity from your UK property. Donald Klip, Co-Founder — Global Mortgage Group.

[email protected] | +65 9773 0273 | www.gmg.asia

This timing mismatch, a tax liability due in six months, against a probate and property sale process that can take considerably longer, creates a genuine liquidity problem for beneficiaries, even where the estate itself, once fully realised, is more than sufficient to cover the liability. Families are sometimes forced into a rushed, discounted property sale purely to raise cash for a tax bill, when a properly structured bridging facility could avoid that forced sale entirely.

How Bridging Finance Solves the Timing Mismatch

A bridging facility secured against the property itself, or against other estate assets, can provide the liquidity needed to settle an inheritance tax liability on time, while the fuller and more considered process of probate, valuation and eventual sale or transfer of the property proceeds on its own timeline. This avoids the value destruction that often accompanies a forced, rushed sale conducted purely to meet a tax deadline rather than to achieve the best price.

"We see families who would clearly be better off waiting eighteen months to sell a Belgravia house properly, forced instead into a rushed six-month sale purely because of an inheritance tax deadline. A bridging facility against the estate is very often the difference between a forced, discounted sale and a considered one at the right time."
- Donald Klip, Co-Founder — Global Mortgage Group

Coordinating With Executors and Probate Solicitors

This kind of facility requires close coordination with the estate's executors and probate solicitors, since the lender needs comfort around the estate's overall position, the expected timeline to probate, and the ultimate source of repayment, whether that is a property sale, other estate assets, or funds contributed by beneficiaries. Families anticipating this kind of liquidity gap, particularly where a UK property forms a significant part of an international family's estate, benefit from planning this financing route in advance rather than scrambling for a solution once a tax deadline is already looming.

Addressing an Inheritance Tax Liquidity Gap

  • UK inheritance tax is generally due within six months of death, often before probate and sale can complete
  • Bridging finance secured against the estate can prevent a forced, discounted property sale
  • Close coordination with executors and probate solicitors is essential to structure this kind of facility
  • Families with significant UK property in an international estate benefit from planning this route in advance

About Global Mortgage Group

Global Mortgage Group (GMG) is a Singapore-headquartered cross-border real estate finance firm operating across 23+ jurisdictions, specialising in equity release, bridging loans and structured property finance for international property owners. GMG works with private clients, family offices and their advisers to unlock capital held in prime residential real estate.

Donald Klip, Co-Founder — Global Mortgage Group

[email protected] | +65 9773 0273 | www.gmg.asia

This is the final article in the Strategy section of GMG's Unlocked in the UK series. The next section covers named developments marketed to overseas investors, starting with Battersea Power Station.

Unlocked in UK: Exit Planning as Prime Central London Moves Into a Recovery Phase

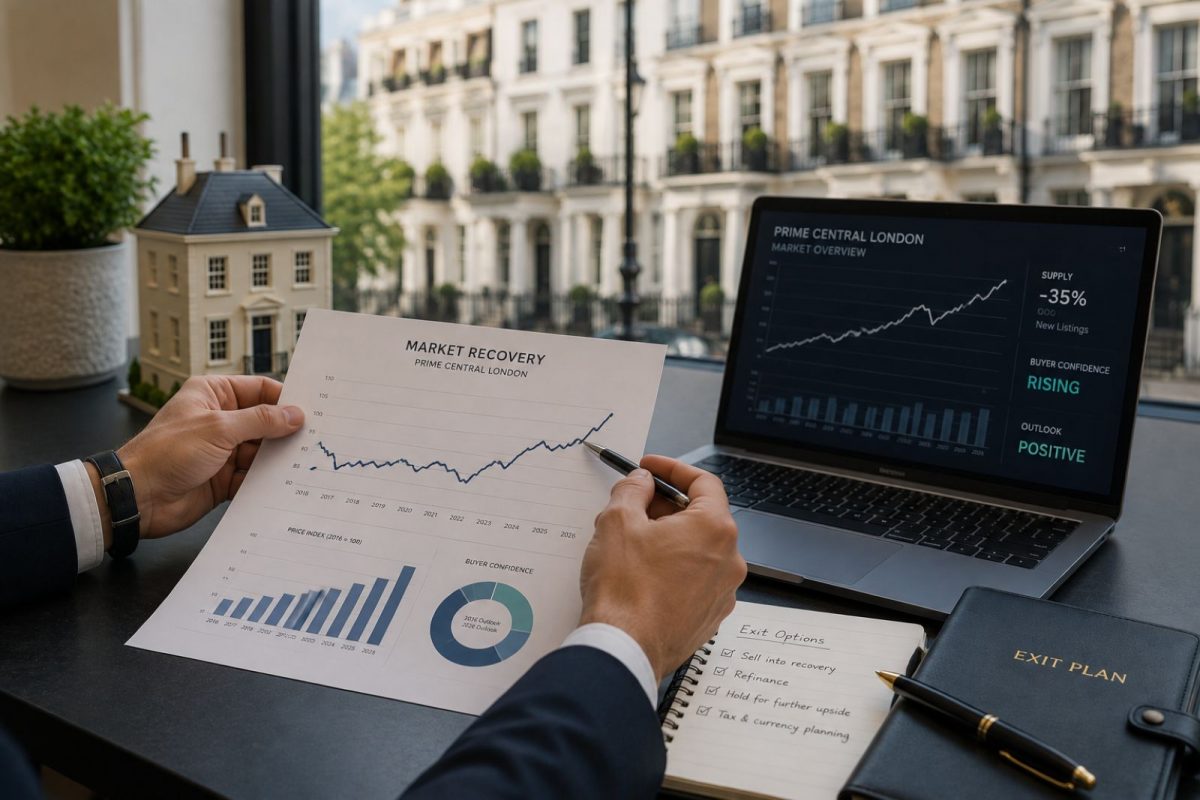
Prime London property owner reviewing market recovery data, representing exit planning strategy for a bridging or equity release facility

Coutts, Savills and other prime central London market observers head into 2026 with cautious but consistent optimism: a market that has been broadly flat to declining for over a decade appears to be approaching, if not already entering, a recovery phase, supported by falling interest rates, improving buyer confidence, and a supply environment tightening enough to support future price growth.

Speak to GMG about releasing equity from your UK property. Donald Klip, Co-Founder — Global Mortgage Group.

[email protected] | +65 9773 0273 | www.gmg.asia

For owners who have used equity release or bridging finance to access capital during the discounted years covered elsewhere in this series, this recovery phase raises an important and often under-planned question: what does the exit from that facility actually look like, and how should it be timed against the broader market recovery, rather than against an arbitrary loan maturity date alone.

Why Exit Timing Deserves as Much Planning as Entry Timing

A facility taken out during the depths of the discounted cycle, structured with a sale or refinance as its intended exit, should ideally be timed to complete once the market has recovered meaningfully, rather than at whatever point the original facility term happens to expire. Facilities structured with flexibility around term length and refinancing options give owners more control over exit timing, allowing them to align a sale or refinance with the market's actual trajectory rather than an inflexible calendar date.

"The clients who do best through a cycle like this one are rarely the ones who timed the entry perfectly. They are the ones who built enough flexibility into the exit that they could wait for the recovery to actually show up in the market, rather than being forced to sell or refinance at a fixed date regardless of where prices happened to be."
- Donald Klip, Co-Founder — Global Mortgage Group

Refinancing Versus Selling at Exit

As the market recovers, owners approaching the end of a bridging or equity release facility face a genuine choice between selling into improved pricing to realise gains, or refinancing onto a longer-term facility to retain the property and continue benefiting from further recovery. This decision should be revisited actively as market conditions evolve, alongside any currency considerations relevant to the owner's home jurisdiction, rather than defaulting to whichever option was originally assumed at the point the facility was first arranged.

Planning an Exit Into a Recovering Market

  • Build flexibility into facility terms rather than committing to a fixed exit date at the outset
  • Revisit the sell-versus-refinance decision actively as market conditions evolve through the recovery
  • Track the broader prime central London recovery, not just the individual property's own valuation
  • Coordinate exit timing with any currency considerations relevant to the owner's home jurisdiction

About Global Mortgage Group

Global Mortgage Group (GMG) is a Singapore-headquartered cross-border real estate finance firm operating across 23+ jurisdictions, specialising in equity release, bridging loans and structured property finance for international property owners. GMG works with private clients, family offices and their advisers to unlock capital held in prime residential real estate.

Donald Klip, Co-Founder — Global Mortgage Group

[email protected] | +65 9773 0273 | www.gmg.asia

This is part of GMG's Unlocked in the UK strategy series. The final article covers inheritance tax-driven bridging finance.

Unlocked in UK: Bridging for Auction and Off-Market Deals as Prime London Supply Tightens

Auction gavel beside a London property listing, representing bridging finance for auction and off-market deals

Supply across prime central London contracted sharply heading into 2026, with new listings down 35 percent quarter on quarter and new instruction volumes running 18 percent below the ten-year average. For buyers, this means the best opportunities increasingly surface off-market, through auction, or via a narrow window before a property is broadly advertised, all of which demand financing speed that a conventional mortgage process cannot deliver, a dynamic explored further in this series' piece on buying into a discounted cycle.

Speak to GMG about releasing equity from your UK property. Donald Klip, Co-Founder — Global Mortgage Group.

[email protected] | +65 9773 0273 | www.gmg.asia

This strategic reality connects directly to the auction buyer profile covered elsewhere in this series, but extends further into off-market transactions more broadly: a well-connected buying agent identifying a property before it reaches the open market, a vendor preferring a quick, certain sale over a longer marketing period, or a probate or divorce-driven sale where speed benefits both sides.

Why a Supply-Constrained Market Rewards Financing Speed Disproportionately

In a well-supplied market, a buyer who loses one opportunity to a faster competitor can generally find another comparable property soon after. In a market where new listings have fallen sharply and open-market stock is down 15 percent quarter on quarter, comparable opportunities are scarcer, and losing a deal to financing delay carries a higher real cost than in a normal market environment.

"The tightening supply we are seeing into 2026 changes the value of speed itself. Two years ago, losing a deal to a slow mortgage process was frustrating but recoverable. Today, with listings down this sharply in the postcodes that matter most, the next comparable opportunity might not appear for months."
- Donald Klip, Co-Founder — Global Mortgage Group

Arranging Financing Before the Opportunity Appears

Given how quickly the best off-market and auction opportunities can move, buyers active in today's constrained supply environment benefit from having financing arranged in principle before a specific property is identified, rather than starting the financing conversation only once an opportunity has surfaced. This is particularly relevant for buyers working with buying agents who specialise in off-market access, where the ability to move immediately is often the deciding factor in securing a property.

Positioning for a Supply-Constrained Market

  • Arrange indicative bridging or equity release facilities before identifying a specific target property
  • Work with buying agents who specialise in off-market access, given the sharp fall in open listings
  • Understand that losing a deal to financing delay carries a higher real cost in today's thin market
  • Balance financing speed against cost, recognising the trade-off is more favourable than usual right now

About Global Mortgage Group

Global Mortgage Group (GMG) is a Singapore-headquartered cross-border real estate finance firm operating across 23+ jurisdictions, specialising in equity release, bridging loans and structured property finance for international property owners. GMG works with private clients, family offices and their advisers to unlock capital held in prime residential real estate.

Donald Klip, Co-Founder — Global Mortgage Group

[email protected] | +65 9773 0273 | www.gmg.asia

This is part of GMG's Unlocked in the UK strategy series. The next article covers exit planning as the market moves into a recovery phase.

Unlocked in UK: Currency Timing for Dollar and Gulf-Currency Buyers in a Discounted Market

Currency exchange chart alongside a London skyline, representing currency timing for dollar and Gulf-currency property buyers

For US dollar buyers and Gulf buyers whose currencies are pegged to the dollar, the combination of a discounted prime central London market and sterling's own exchange rate movements over the past decade has created a genuinely rare double effect on purchasing power: buying an asset priced well below its own historic peak, in a currency that has, at various points, also strengthened against sterling.

Speak to GMG about releasing equity from your UK property. Donald Klip, Co-Founder — Global Mortgage Group.

[email protected] | +65 9773 0273 | www.gmg.asia

This dynamic does not apply uniformly across every buyer group covered in this series, mainland Chinese and Indian buyers, for instance, face capital control and remittance constraints that shape their transactions in different ways, as covered in their respective nationality guides. But for dollar and dollar-pegged currency buyers specifically, currency timing deserves as much attention as the underlying property price.

Why Timing the Currency, Not Just the Property, Matters

A buyer who focuses only on negotiating the best possible sterling purchase price, while ignoring the prevailing exchange rate at the point of completion, can leave a meaningful amount of value on the table relative to a buyer who also pays attention to currency timing. Facilities can sometimes be structured to allow a degree of flexibility in the drawdown or completion timeline specifically to accommodate favourable currency movements, though this needs to be balanced against the practical realities of vendor timelines and exchange deadlines.

"We regularly see buyers negotiate hard on the sterling price and then convert their currency without a second thought, at whatever rate happens to apply on the day. Given how much movement we have seen in GBP over the past decade, that is often a bigger swing in real cost than anything achieved in the price negotiation itself."
- Donald Klip, Co-Founder — Global Mortgage Group

Structuring for the Eventual Exit, Not Just the Entry

Currency considerations apply just as much to the eventual sale or refinance of a UK property as to the original purchase. A dollar-based buyer who purchased when sterling was weak and sells or refinances when sterling has strengthened experiences a currency headwind on exit that can offset some of the entry-point advantage. Building this into the original financing strategy, rather than treating currency as relevant only at the point of purchase, produces a more complete and realistic long-term plan.

Currency Planning Considerations for Dollar and Gulf-Currency Buyers

  • Track sterling's exchange rate trend, not just the property's sterling price, when timing a purchase
  • Consider whether facility drawdown timing offers any flexibility to align with favourable currency movements
  • Plan for currency exposure on the eventual exit, not only at the point of purchase
  • Coordinate currency and property market timing together rather than treating them as separate decisions

About Global Mortgage Group

Global Mortgage Group (GMG) is a Singapore-headquartered cross-border real estate finance firm operating across 23+ jurisdictions, specialising in equity release, bridging loans and structured property finance for international property owners. GMG works with private clients, family offices and their advisers to unlock capital held in prime residential real estate.

Donald Klip, Co-Founder — Global Mortgage Group

[email protected] | +65 9773 0273 | www.gmg.asia

This is part of GMG's Unlocked in the UK strategy series. The next article covers bridging finance for auction and off-market deals in a supply-constrained market.

Unlocked in UK: Buying Into a Discounted Cycle — What the 2013-Level Pricing Window Actually Means

Prime London street of townhouses representing a discounted buying cycle and equity release opportunity

Coutts' latest London Prime Property Index, published in February 2026, delivered a striking headline: prices in many prime central London hotspots have effectively reverted to levels last seen in 2013, more than a decade of nominal stagnation in some of the world's most sought-after postcodes. For buyers and existing owners alike, understanding what this actually means, and what it does not, is central to making good financing decisions in the current cycle.

Speak to GMG about releasing equity from your UK property. Donald Klip, Co-Founder — Global Mortgage Group.

[email protected] | +65 9773 0273 | www.gmg.asia

Across the prime market as a whole, values sit around 10.3 percent below their 2014 peak. Knightsbridge and Belgravia are trading roughly 29.5 percent below their previous highs, and Chelsea remains around 20.5 percent off its own peak. These are not small adjustments, and they have persisted for over a decade rather than resolving in a typical multi-year correction.

Why This Is a Buying Window Rather Than a Warning Sign

A market that has been flat or declining for over a decade can look, superficially, like a market to avoid. The more useful read, echoed across Coutts, Savills and Knight Frank commentary heading into 2026, is that this represents genuine long-term value for buyers able to take a patient, multi-year view, particularly given supply has contracted sharply, new listings down 35 percent quarter on quarter into early 2026, just as buyer confidence begins to recover.

"A decade of flat prices in Knightsbridge or Belgravia is not a market that has failed. It is a market that has fully priced in over a decade of headwinds, Brexit uncertainty, tax changes, a global pandemic, and is now sitting at levels that most serious analysts expect to recover over time, even if nobody can call the exact turning point."
- Donald Klip, Co-Founder — Global Mortgage Group

How This Shapes Financing Decisions

For existing owners, this environment strongly favours borrowing against a property to access capital rather than selling into a discounted market, since a sale locks in today's depressed pricing permanently, while a facility allows the owner to benefit from any future recovery. For buyers, it argues for entering the market now, while discounting is at its most pronounced and new-build and resale supply is constrained, particularly in areas like Belgravia, rather than waiting for a recovery that may already be underway by the time it becomes obvious in the headline data.

What the Current Pricing Window Means in Practice

  • Existing owners: releasing equity, rather than selling, preserves upside if the market recovers
  • Buyers: entering during a supply-constrained, discount period may offer better long-term value than waiting
  • Knightsbridge, Belgravia and Chelsea currently show the deepest discounts from their 2014 peaks
  • Supply contraction into 2026 may support pricing before broader recovery becomes widely recognised

About Global Mortgage Group

Global Mortgage Group (GMG) is a Singapore-headquartered cross-border real estate finance firm operating across 23+ jurisdictions, specialising in equity release, bridging loans and structured property finance for international property owners. GMG works with private clients, family offices and their advisers to unlock capital held in prime residential real estate.

Donald Klip, Co-Founder — Global Mortgage Group

[email protected] | +65 9773 0273 | www.gmg.asia

This is part of GMG's Unlocked in the UK strategy series. The next article covers currency timing for dollar and Gulf-currency buyers.

Unlocked in UK: Thai Buyers — Established Family Wealth and the UK Education Tradition

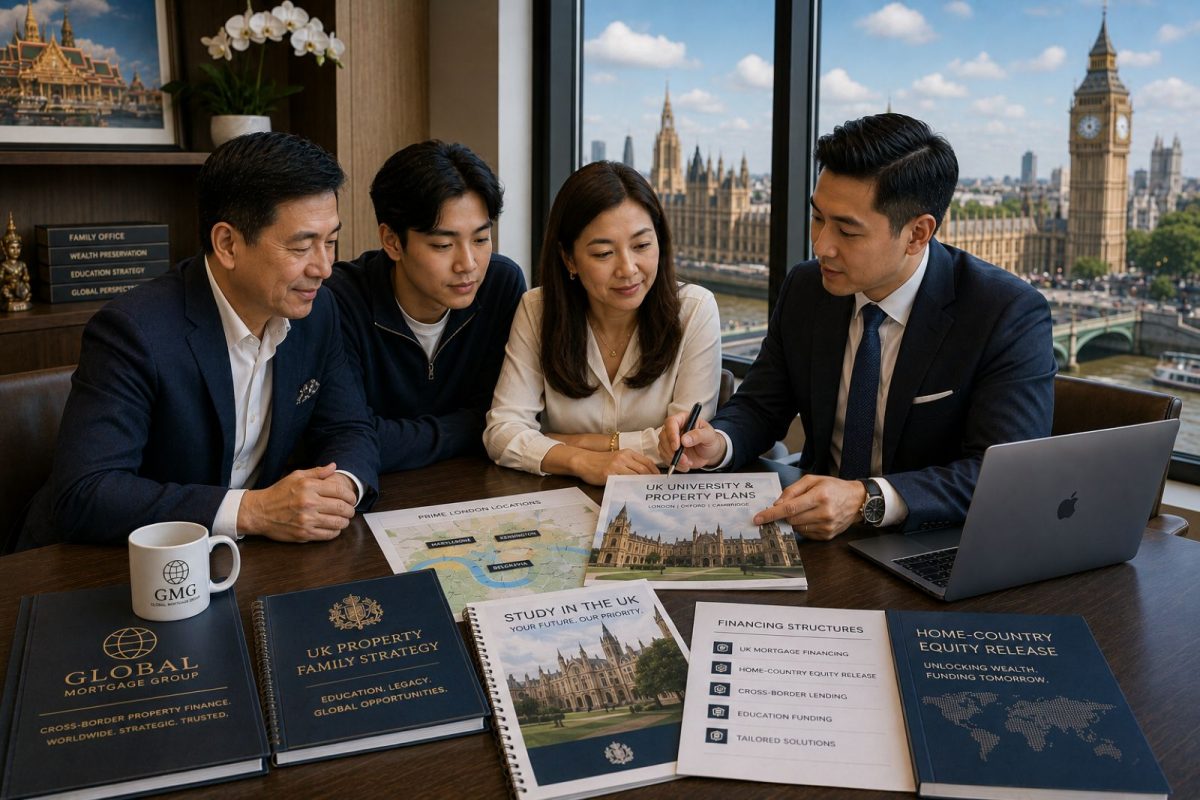
Thai family reviewing UK university and property plans, representing Thai buyer financing for UK property

Thailand's connection to UK property runs through a long-standing tradition of British education among Thai business and professional families, reinforced by Thailand's own network of British-curriculum international schools that feed naturally into UK universities. For many Thai families, a UK property purchase is the logical extension of an educational relationship that may already span generations.

Speak to GMG about releasing equity from your UK property. Donald Klip, Co-Founder — Global Mortgage Group.

[email protected] | +65 9773 0273 | www.gmg.asia

Thai buyers are typically drawn from established business families and senior professionals, and their purchases skew toward central London and university-proximate locations rather than the yield-driven investment segment. The motivation is more often a family base with an educational purpose than a pure investment allocation, though the two frequently coexist in the same transaction.

Bank of Thailand Regulations and Outbound Transfers

Thailand maintains foreign exchange regulations administered by the Bank of Thailand governing outbound transfers, including for overseas property purchase. These are considerably less restrictive than Vietnam's or China's, but they are not absent, and larger transactions require proper documentation and planning rather than an assumption that funds can simply be wired on demand. Thai buyers should establish the mechanics early, particularly where a purchase timeline is driven by an academic year.

"Thai families often have a very clear sense of the school or university and a very fixed date attached to it. The financing has to work backwards from that date, and the Bank of Thailand transfer mechanics need to be part of the plan from the start rather than a surprise in the final fortnight."
- Donald Klip, Co-Founder — Global Mortgage Group

The Thailand Connection and GMG's Own Footprint

GMG's cross-border practice includes a substantial Thailand presence, and the reverse transaction, releasing equity from Thai property to fund purposes elsewhere, is covered extensively in GMG's separate Unlocked in Thailand series. For a Thai family holding significant domestic property wealth and wanting to fund a UK purchase, the home-country equity release route covered in this series' university buyer section is frequently the most efficient structure, allowing the family to fund a UK acquisition without liquidating Thai assets or moving large sums from onshore Thai holdings.

The baht's movement against sterling is a further consideration for both the timing of a purchase and the eventual position on exit, and Thai families should model that dimension rather than assessing the sterling numbers in isolation.

Financing Considerations Specific to Thai Buyers

  • Bank of Thailand foreign exchange rules require planning, though they are less restrictive than Vietnam's or China's
  • Education-driven timelines are often fixed to an academic year; work the financing backwards from that date
  • Releasing equity from Thai property to fund a UK purchase is frequently the most efficient structure
  • Purchases skew toward central London and university-proximate family bases rather than yield investment

About Global Mortgage Group

Global Mortgage Group (GMG) is a Singapore-headquartered cross-border real estate finance firm operating across 23+ jurisdictions, specialising in equity release, bridging loans and structured property finance for international property owners. GMG works with private clients, family offices and their advisers to unlock capital held in prime residential real estate.

Donald Klip, Co-Founder — Global Mortgage Group

[email protected] | +65 9773 0273 | www.gmg.asia

This is the final article in the Asia Pacific nationality section of GMG's Unlocked in the UK series. The next section covers strategy. See also GMG's Unlocked in Thailand series for the reverse transaction: releasing equity from Thai property.