Spain Mortgages for Non-Residents: Invest Like a Local Without Living There

Spain property financing
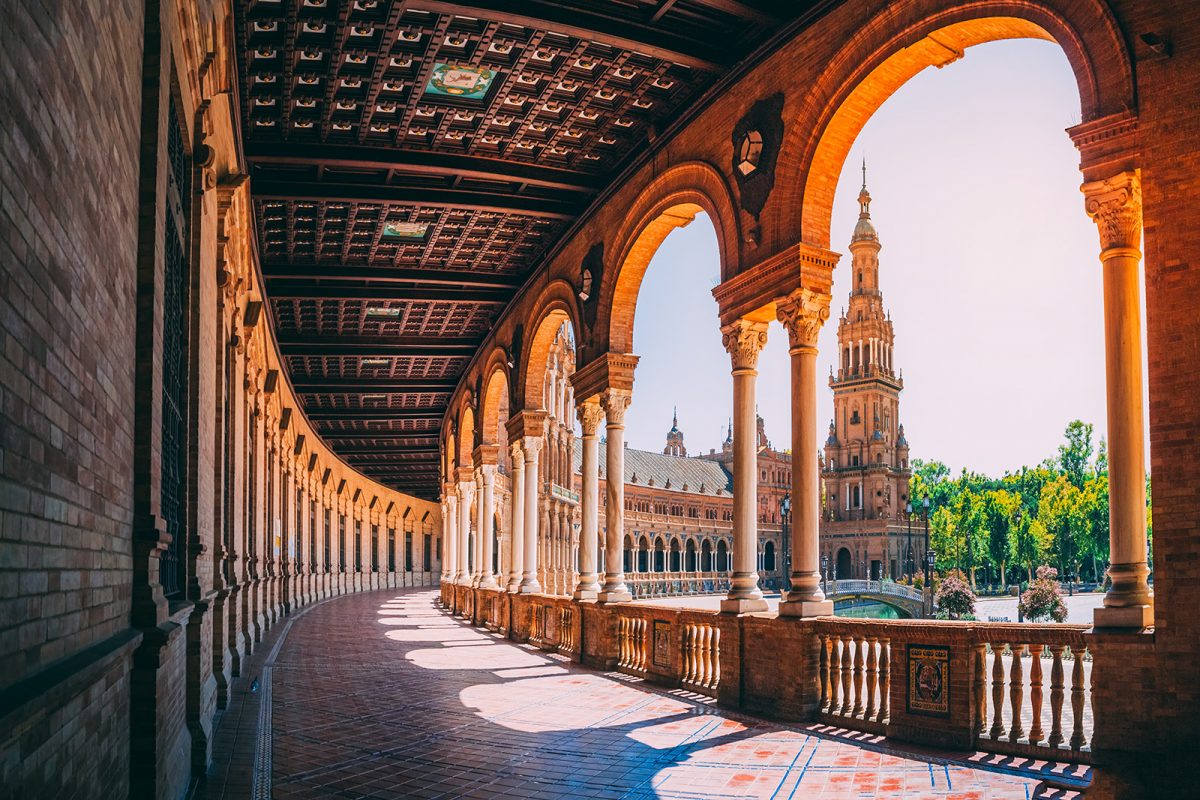
A beautiful view of the Plaza de Espana in Seville in Spain

What You Will Learn

  • How Spain mortgages for non-residents are structured and approved
  • What international buyers need to qualify without Spanish residency
  • How bank mortgages compare with private and bridge financing options
  • Common mistakes non-resident investors make when buying in Spain
  • How global investors finance Spanish property while living abroad

Why Spain Attracts Non-Resident Property Investors

Spain remains one of Europe’s most attractive real estate markets for international buyers. Strong rental demand, lifestyle appeal, and a clear legal framework continue to draw overseas investors seeking euro-denominated assets and long-term stability.

Unlike many countries that restrict financing to residents, Spain allows non-residents to legally purchase and mortgage property, even if they live entirely outside the country. This aligns closely with broader cross-border strategies outlined in how to finance international property without being a citizen or resident, where ownership and financing are structured independently of residency.

Foreign demand is well established. According to data published by the Banco de España, international buyers consistently account for a meaningful share of residential transactions, reinforcing Spain’s openness to global capital.

How Spain Mortgages for Non-Residents Actually Work

Spain mortgages for non-residents follow a defined structure, although terms differ from resident lending.

In most cases, overseas buyers can expect:

  • Loan-to-value ratios of 60–70 percent
  • Mortgage terms of up to 20–25 years, depending on age and profile
  • Interest rates slightly higher than resident mortgages
  • Full assessment of global income, assets, and liabilities

Residency is not the deciding factor. Spanish lenders focus on financial stability, income continuity, and exit planning. This approach reflects the principles explained in the secret to financing international property as a non-resident, where overseas income is treated as a core qualification metric.

Real-Life Example: Buying in Spain While Living Abroad

Consider a Singapore-based investor purchasing a two-bedroom apartment in Valencia as a long-term rental. The buyer has no Spanish residency and earns income entirely outside Europe. A Spanish bank is willing to lend, but approval timelines extend beyond the seller’s deadline.

In this scenario, investors often use short-term acquisition funding, complete the purchase, and then refinance once ownership is secured. This strategy mirrors the approach explained in what bridge financing is and how it benefits investors, particularly in competitive European markets where speed matters.

By separating purchase execution from long-term financing, non-resident buyers reduce risk while preserving opportunity.

Bank Mortgages vs. Private Financing for Non-Residents

Spanish banks remain a viable option for some international buyers, but approval processes can be slow and documentation-heavy. Requirements such as local accounts, translated records, and extended underwriting often limit flexibility.

As a result, many overseas investors adopt broader financing strategies similar to those described in mortgage solutions for global investors who live abroad and invest anywhere. These structures rely on cross-border lending expertise rather than a single local bank.

Failing to plan financing early remains one of the most common mistakes among non-resident buyers. This risk is outlined in avoiding the mistake of buying international property without a mortgage plan, where lack of preparation leads to delayed or failed transactions.

Legal and Regulatory Framework for Non-Resident Buyers

Spain offers one of Europe’s most transparent property ownership systems. Non-residents must obtain an NIE (foreigner identification number) and register ownership through Spain’s land registry.

The Colegio de Registradores de España, the official body overseeing property registration, provides legal certainty and ownership protection for foreign buyers. This clarity makes Spain particularly attractive for long-term international investors.

From a tax perspective, non-residents should plan for transfer tax or VAT, annual non-resident income tax on rental income, and ongoing property costs. Proper mortgage structuring helps align financing with these obligations.

Why Spain Is Considered Mortgage-Friendly for Non-Residents

Spain consistently ranks among Europe’s most accessible markets for overseas buyers due to predictable regulations, strong lender participation, and sustained foreign demand.

These characteristics place Spain alongside other leading destinations featured in GMG’s top mortgage-friendly countries for non-resident buyers in 2025.

For investors building diversified international portfolios, Spain offers a balance of financing access, lifestyle appeal, and long-term market stability.

Speak With a Global Mortgage Specialist

Spain mortgages for non-residents are achievable, but results depend on structure, timing, and lender strategy. At Global Mortgage Group, we work with international investors who want to invest like locals while living abroad, ensuring financing aligns with long-term portfolio goals rather than short-term approvals.

Whether you are purchasing your first Spanish property or expanding a multi-country portfolio, our specialists provide tailored, compliant solutions. Contact us at [email protected] or connect through our GMG contact page to discuss your Spain investment strategy with confidence. Learn more about our expertise on the Global Mortgage Group page.

Summary

Spain remains one of Europe’s most attractive property markets for non-resident investors. While mortgage terms differ from resident loans, international buyers can successfully secure financing without living in Spain. With the right planning and cross-border expertise, non-residents can invest efficiently while maintaining global mobility.

Frequently Asked Questions

Q1: Can non-residents get a mortgage in Spain without living there?

A: Yes. Spain mortgages for non-residents are based on global income and financial strength, not residency.

Q2: What loan-to-value ratios apply to non-resident mortgages in Spain?

A: Most lenders offer 60–70 percent LTV, depending on borrower profile and property type.

Q3: Is bridge financing common for overseas buyers in Spain?

A: Yes. Bridge financing is frequently used to secure properties quickly before refinancing into long-term structures.

Q4: Do non-residents need Spanish income to qualify?

A: No. Foreign income is acceptable when properly documented and assessed.

Q5: Who should manage financing for non-resident buyers?

A: Specialists experienced in international property finance, such as Global Mortgage Group, help align mortgages with cross-border investment goals.

How to Finance Canadian Property as a Non-Resident Buyer

Canadian real estate for global investors

What You Will Learn

  • How non-residents can finance Canadian property without local income or residency
  • What lenders evaluate when assessing foreign buyers
  • How bridging loans help investors act quickly in competitive markets
  • Tax considerations for international investors
  • How GMG structures global financing strategies for Canadian purchases

Financing Canadian Property as a Non-Resident Buyer

Canada remains one of the most stable real estate markets in the world. Strong immigration-driven demand, limited supply in major cities, and a rule-of-law environment attract global investors every year. But many non-residents assume they cannot finance Canadian property unless they live in the country.

The truth is simple:
Foreign buyers can access property financing in Canada, but they must meet specific non-resident lending requirements.

GMG works with global investors every day who finance homes, condos, and rental properties across Canada through cross-border income, offshore assets, and tailored lending solutions.

For investors exploring opportunities in the U.S. as well, GMG details similar structures in its overview of U.S. mortgage options for international buyers.

Why International Investors Buy in Canada

  • Stable long-term price appreciation
  • Consistent rental demand in Toronto, Vancouver, Montreal, Calgary
  • Strong currency fundamentals over long horizons
  • Predictable property laws and transparent legal processes

Canada also benefits from its reputation as a safe haven. During periods of global uncertainty, capital flows back into Canadian real estate, especially from Asia, the Middle East, and Europe.

GMG’s macro research on global investment shifts, such as How International Investors Use Property Financing in 2026, highlights this trend clearly.

How Non-Residents Finance Canadian Property

Canada’s lending ecosystem allows non-residents to borrow even without local income or residency, though underwriting standards differ from resident buyers.

1. Loan-to-Value (LTV) Guidance

Most foreign buyers qualify for:

  • 65%–75% LTV for condos and single-family homes
  • Lower LTVs for rural or non-standard properties

Foreign nationals must typically provide higher down payments due to risk-based lending guidelines.

2. Income Assessment

Canadian lenders do not require Canadian employment. Instead, they review:

  • Global income streams
  • International employment contracts
  • Corporate or business income (audited or validated)
  • Credit reports from country of residence

This aligns with how GMG evaluates borrowers globally across 21 mortgage markets.

3. Documentation Standards

Non-residents should expect to provide:

  • Passport + second ID
  • International bank statements (3–6 months)
  • Global tax documentation or CPA letters
  • Credit report from the home country
  • Proof of funds for down payment + closing costs

Bridging Loans: A Faster Path for Canadian Purchases

In competitive Canadian cities, especially Toronto and Vancouver, buyers often need funds quickly to secure a unit before arranging a long-term mortgage.

GMG frequently structures a bridge loan + mortgage strategy for global investors:

  1. Bridge financing provides immediate liquidity
  2. Transition to a long-term mortgage once documents and approvals are completed

This approach is widely used among sophisticated investors globally.

Key Tax Considerations for Foreign Buyers

Foreign investors in Canada must be aware of:

1. Withholding Tax on Rental Income

Non-resident investors may face withholding tax on rental revenue unless they file an NR6 and annual Section 216 return.

2. Capital Gains Tax

Any sale of Canadian property by a non-resident triggers a clearance certificate and capital gains calculation. GMG outlines global comparisons in Real Estate Capital Gains Tax: A Global Comparison.

3. Provincial Foreign Buyer Taxes

Some provinces previously imposed foreign buyer taxes. Many of these have been reduced or eliminated in recent policy changes, but may still apply in specific regions.

Always cross-check official guidance via Government of Canada housing and tax resources.

Real Example: How Investors Finance Canadian Property

Scenario:
A Singapore-based investor wants to purchase a CAD 900,000 Toronto condo as a rental property.

GMG Strategy:

  • Structured a 70% LTV non-resident mortgage using foreign income
  • Used a short-term bridge loan to secure the offer while documents were reviewed
  • Integrated Canadian tax filing guidance and cross-border financing advice

This is similar to what many non-resident investors do in the U.S., Japan, Australia, and Europe, as reflected in GMG’s insights from the Top 5 Countries with the Easiest Property Financing Options.

Why Work With GMG for Canadian Property Financing

Financing Canadian property as a non-resident requires cross-border expertise, global income underwriting, and lenders who understand overseas borrowers. GMG streamlines this process by connecting investors to mortgage programs built specifically for international buyers while coordinating short-term and long-term financing strategies across global portfolios.

GMG’s advisory team supports clients from initial assessment to final approval, ensuring every step aligns with broader investment goals. You can learn more about the team on the About Us page and explore broader insights in the Global Property Financing Q&A. For personalised guidance on securing your Canadian mortgage, contact [email protected].

Frequently Asked Questions

Q1. Do I need Canadian credit to finance Canadian property?

A: No. Most lenders accept foreign credit reports and global income documentation. They primarily assess overall financial strength, not local borrowing history.

Q2. Can I get financing even if I don’t live or work in Canada?

A: Yes. Non-resident mortgages are designed specifically for overseas buyers with international income. Lenders structure approvals around verifiable global earnings and assets.

Q3. Can bridging loans be used for Canadian real estate?

A: Absolutely. Many investors use bridging loans for fast deposits or to buy before selling another property abroad. This allows buyers to act quickly in competitive markets before transitioning into long-term financing.

No Visa, No Problem—Countries Where Foreigners Can Get Mortgages Easily

non-resident mortgages

What You Will Learn

  • Why residency and visas are not always required to get a mortgage
  • Which countries actively offer mortgages to foreign buyers
  • How lenders assess non-resident borrowers without local credit
  • Common mistakes international buyers make when financing abroad
  • How global investors structure mortgages across multiple countries

Why You Do Not Need a Visa to Get a Mortgage

A common misconception among international buyers is that a residence visa or long-term permit is required before financing property abroad. In reality, mortgages and immigration are separate legal systems in most countries, a distinction Global Mortgage Group (GMG) works with daily when structuring cross-border property financing.

Lenders focus on property value, borrower strength, and exit strategy, not where you live. This distinction is the foundation of cross-border financing strategies explained in how to finance international property without being a citizen or resident.

As global real estate investment becomes more normalized, banks and private lenders increasingly design products specifically for non-resident borrowers.

Countries Where Foreigners Can Get Mortgages Easily (No Visa Required)

Foreigners can obtain mortgages without visas or residency in several countries, but success depends on whether the market has institutional non-resident lending frameworks, not simply whether foreigners are allowed to buy property. In practice, only a subset of countries offers repeatable, scalable mortgage access for overseas buyers.

Tier-1 Countries: Proven, Mortgage-Friendly for Foreigners

These countries consistently support non-resident mortgages using global income, offshore assets, and conservative loan structures. They are the most reliable markets for international buyers seeking financing without visas.

United States

The United States remains the most accessible mortgage market for foreigners globally. Non-residents can finance residential, luxury, and investment property without U.S. visas or residency, often using foreign income and bank statements instead of local credit. This structural openness explains why global capital continues flowing into U.S. real estate, as highlighted in why foreign investors are pouring billions into U.S. real estate and U.S. luxury property investments attracting global buyers.

Spain

Spain offers one of Europe’s clearest non-resident mortgage frameworks. Foreign buyers can finance property without residency, typically at lower loan-to-value ratios than residents. Lending decisions focus on income strength and property quality rather than immigration status, making Spain a core destination for overseas investors.

Australia

Australia supports non-resident mortgages for approved properties, particularly when borrowers demonstrate strong equity positions or global income. Many overseas owners treat Australian property as a capital base, unlocking equity while living abroad. This makes Australia especially attractive for investors using cross-border portfolio strategies.

Portugal

Portugal continues to attract foreign buyers with structured non-resident lending, particularly for long-term investment and lifestyle-driven purchases. While underwriting is conservative, financing is well established for overseas borrowers without visas.

These Tier-1 markets are consistently referenced in where global real estate investors can get non-resident mortgages and expanded further in how to finance property in countries that welcome non-residents.

Tier-2 Countries: Possible, But More Selective

Other countries do offer non-resident mortgages, but access is more selective and profile-dependent. These markets are viable for high-net-worth borrowers or structured cases, rather than broad investor access.

  • United Kingdom: Non-resident buy-to-let lending is available, but with higher rates and tighter affordability
  • France: Conservative underwriting, strong documentation requirements
  • Germany: Selective foreign lending, typically through private banks
  • Singapore: Technically possible but heavily restricted and equity-driven

For most international buyers, Tier-2 markets require advanced planning and specialist structuring, which is why GMG focuses on solutions outlined in how to get global real estate loans with no local credit or residency and the secret to financing international property as a non-resident.

Why These Countries Work Without Visas

Across mortgage-friendly jurisdictions, lenders assess financial substance, not immigration status. Approval typically depends on:

  • Global income and asset strength
  • Conservative loan-to-value ratios
  • Market liquidity and resale risk
  • A clear exit strategy rather than residency intent

This approach reflects broader international lending standards supported by institutions such as the World Bank, which documents cross-border property rights and financial system stability, and the OECD, which tracks international capital flows into real estate markets.

The Strategic Takeaway for Global Investors

Foreigners do not need visas to get mortgages in many of the world’s most active property markets. What matters is choosing countries with proven non-resident lending systems and structuring finance before selecting property. Investors who skip this step often encounter delays or failed transactions, a risk explained in avoiding the mistake of buying international property without a mortgage plan.

For investors living abroad, the most efficient approach is to focus on Tier-1 markets and apply a global financing framework, as outlined in mortgage solutions for global investors who live abroad and invest anywhere.

How Lenders Approve Mortgages Without Residency

When visas and local credit are removed from the equation, lenders rely on a different risk framework.

Typically assessed factors include:

  • Global income and asset strength
  • Property location and liquidity
  • Conservative loan-to-value ratios
  • Clear exit strategy rather than long-term residency

These principles are explored further in how to get global real estate loans with no local credit or residency, and the secret to financing international property as a non-resident.

Real-Life Example: Buying Without a Visa

A Dubai-based investor purchases a rental property in the United States without holding a visa or spending time in the country. Financing is approved using foreign income, bank statements, and a conservative LTV structure.

The investor later refinances and redeploys equity into another market, following the same global approach described in mortgage solutions for global investors who live abroad and invest anywhere.

This strategy demonstrates how visas are often irrelevant to well-structured property finance.

The Most Common Mistake Foreign Buyers Make

The biggest mistake international buyers make is assuming financing will be arranged after a property is found. Without advance planning, deals fall apart due to timing, documentation, or lender mismatches.

This risk is explained in avoiding the mistake of buying international property without a mortgage plan. Experienced investors reverse the process, securing a financing strategy first, then selecting the market and property. Global Mortgage Group helps foreign buyers structure non-resident mortgage strategies early, reducing delays and deal risk.

Market Conditions That Support Non-Resident Mortgages

Non-resident mortgage lending is supported by strong global financial oversight and standardized banking risk frameworks. Institutions such as the Bank for International Settlements set international capital adequacy and cross-border lending standards that guide how banks assess foreign borrowers and property-backed risk.

At the same time, global capital mobility and cross-border investment flows are monitored by the International Monetary Fund, reinforcing lender confidence in international property finance and non-resident mortgage structures.

Together, these frameworks explain why non-resident mortgages are increasingly standardized rather than treated as exceptions.

Finance Property Anywhere—Without Needing a Visa

Residency should never be a barrier to global property ownership. At Global Mortgage Group, we help international buyers structure mortgages in countries that actively welcome foreign borrowers, even without visas or local credit.

If you are evaluating global property opportunities and want clarity on where and how you can finance without residency, speak with our specialists. Contact us at [email protected] or reach out via our contact page to discuss your options with confidence.

Summary

You do not need a visa to get a mortgage in many of the world’s most active property markets. Countries such as the United States, Spain, Australia, and Portugal offer established frameworks for non-resident financing. With the right planning and advisory support, international buyers can access global real estate opportunities without relocating.

Frequently Asked Questions

Q1: Can foreigners really get mortgages without visas?

A: Yes. Many countries separate immigration status from mortgage eligibility.

Q2: What matters more than residency when applying?

A: Global income, asset strength, and property quality are the primary factors.

Q3: Are interest rates higher for non-residents?

A: Often yes, but this varies by country and lender.

Q4: Do I need local credit history?

A: In many cases, no. Lenders assess international credit and banking profiles instead.

Q5: Who should guide the non-resident mortgage strategy?

A: Specialists experienced in cross-border financing, such as Global Mortgage Group, help structure mortgages aligned with global investment goals.

2026 Macro Outlook: My Forecasts + What High Net Worth Global Investors Need to Know

Stacked coins with miniature houses and a hand placing another property model, representing global real estate investment trends and strategic positioning for high-net-worth investors in the 2026 macro outlook.

Former hedge fund manager. 30+ years in institutional finance. I invest and advise through a macro-thematic framework — identifying the structural forces reshaping global monetary policy and capital markets before consensus catches up. As Co-founder of GMG and America Mortgages, I live at the intersection of macro and property markets every day.

Introduction

These are my personal investment convictions for 2026 — which also drives our house view. My approach is top-down: identify the macro regime, then find the assets that benefit before consensus catches up. Right now the regime is pointing toward US Treasury market stress, an inevitable Fed pivot, and a 2H 2026 that looks nothing like today. For high net worth investors, family offices, and international buyers of US real estate, the implications are direct and actionable.

1. The 10-year Treasury Will Break 4.50% — And Washington Cannot Afford It

My thesis starts in the repo market, not in equities or the Fed's dot plot. US repo markets are showing persistent funding stress that mainstream commentary ignores. Japanese institutions — historically the world's most reliable buyers of US Treasuries — are reassessing their appetite as the Bank of Japan normalises. When the most reliable buyer becomes reluctant, the long end of the curve has only one direction.

My call: the 10-year breaks 4.50% before mid-2026. But 4.50% is not just a technical level. It is a fiscal pain threshold — because the stock market is now a primary revenue source for the US government.

The Numbers That Matter:

Individual income taxes = ~50% of $4.9T in FY2024 federal receipts. Capital gains = ~11% of that. Capital gains revenue collapsed 41% during the dot-com bust and 49% in 2008-09. Washington is running a $1.8T annual deficit. It cannot stomach a sustained equity and bond selloff simultaneously. The 10-year yield and the S&P 500 are fiscally joined at the hip.

Watch for any aggressive policy announcement — particularly on trade — that triggers simultaneous equity selling and bond selling. That combination is the tripwire that forces a pivot. The bond market is the world's most powerful negotiating counterparty.

2. Tariffs Are An Inflation Impulse. AI Productivity Is Not Coming In 2026.

Two narratives are competing for the inflation outlook and both are being misread.

Tariffs are a one-time price level step-up, not a structural inflation driver. But 'just an impulse' at exactly the wrong moment in the rates cycle is enough to extend market discomfort through H1. The Fed will respond to the optics as much as the reality.

The AI productivity bull case is real — but not in 2026. Transformative technology delivers its productivity dividend a decade after the investment wave, not the same quarter. The electrification of manufacturing, the internet build-out — both showed up in the data long after the hype. Anyone building a 2026 macro thesis around AI-driven disinflation is getting the timing badly wrong.

3. The FED Will Blink: 2020-style QE, Then Yield Curve Control

Once the 10-year breaks 4.50% with force, the Fed moves. The programme will have a new name — 'market functioning' — but it will be functionally identical to 2020-era QE. The actual objective: keep US sovereign borrowing costs manageable.

The longer-term destination is Yield Curve Control. Japan got there first. The US will resist the label but follow the logic: cap a point on the curve to prevent a sovereign funding crisis. We take the first steps in 2026.

For mortgage rates: 6–7% in 2026. The Fed's long-end suppression provides a ceiling. A return to 3% is not coming — that was a historical anomaly, not a baseline.

4. US Real Estate Prices Will Surge In 2h 2026: The YCC And Cap Rate Thesis

The conventional wisdom: higher rates equal lower property prices. My thesis inverts it — specifically for 2H 2026.

When YCC suppresses the long end, three forces converge simultaneously: mortgage rates ease toward the lower end of the 6–7% band, unlocking sidelined buyer demand; a weakening dollar makes USD-denominated assets significantly cheaper for Asian, European, and Middle Eastern buyers on a currency-adjusted basis; and in a QE environment with residual inflation, real assets become the obvious store of value.

Cap rates in US real estate have been pushed wide by three years of rate pressure. When liquidity improves and the long end is capped, cap rate compression happens fast. Investors in the market before that compression capture the full move. This is the window I am positioning around for 2H 2026.

"My on-the-record call for December 2025: US real estate will have one of its best six-month periods in recent memory in 2H 2026."

For International And Expat Buyers:

Dollar weakness provides an effective price discount for Singapore, Hong Kong, Asian, and European buyers. QE improves financing terms. The structural supply deficit supports long-term values. America Mortgages specialises exclusively in US mortgage financing for this buyer profile.

5. The Dollar Is The Only Release Valve — DXY Breaks 80, Tests 75

My bearish DXY view is a policy logic call, not just a monetary mechanics one.

The US is simultaneously pursuing low interest rates, sustained growth, manufacturing reshoring, and fiscal stability. You cannot have all four with a strong dollar. Reshoring requires price-competitive exports — impossible with a strong USD. QE is dollar-negative. Inflating away $35 trillion of debt requires currency erosion over time. The dollar is the only variable that can absorb all the contradictions at once.

Low Rates + Growth + Manufacturing Reshoring + Strong Dollar = Impossible.

The USD has to be the release valve. That is not a forecast — it is arithmetic. DXY breaks 80, tests 75 in 2H 2026.

For global investors: a DXY move of this scale reprices every USD-denominated asset class. It is rocket fuel for gold, silver, aluminium, and US real estate valued in foreign currencies. Position accordingly.

6. Bearish Legacy Software: AI Platforms Will Displace The Interface Layer

I am structurally bearish on legacy software businesses. When an AI agent can perform the task that required a dedicated application, the application becomes redundant. Value migrates to whoever owns the data, the infrastructure, or the content relationships — not the software layer in between.

I cannot see Spotify in its current form in five years. Not because music streaming disappears — but because discovery, curation, and consumption will be AI-native, accessed through conversational platforms rather than dedicated subscription apps. The same logic applies across productivity software, enterprise tools, and consumer platforms. The businesses worth owning are those with irreplaceable data assets or AI infrastructure. Everything else is at risk.

"The interface layer is being replaced. The question is who owns what sits above and below it."

7. Data Centre Capital Requirements: Staggering In Scale, A Hidden Macro Headwind

The AI infrastructure build-out is one of the most significant capital deployment stories in a generation — and at GMG, we are seeing it first-hand. We are actively financing data centre transactions across Asia-Pacific, and the deal sizes, velocity, and appetite for capital are unlike anything I have seen in thirty years.

The macro implication that fewer people are discussing: the volume of capital required to build AI infrastructure — from equity markets, debt capital, infrastructure funds, and private credit — is a meaningful headwind for every other asset class competing for institutional allocation. Every dollar committed to a hyperscaler data centre in Southeast Asia is a dollar not going into residential real estate, commercial property, or traditional fixed income.

For private credit providers with regional expertise, the financing gap is significant. The structures required — construction bridges, complex ownership arrangements, power infrastructure dependencies across multiple Asian jurisdictions — are not served well by traditional bank lending. This is where GMG Capital & Advisory is actively deploying. The opportunity is real; so is the macro drag on everything competing with it for capital.

8. Geopolitics: Sphere-of-influence Crystallisation And Rising Risk Premiums

2026 accelerates sphere-of-influence crystallisation rather than direct confrontation. The US consolidates in Latin America — Venezuela, given its energy significance and geographic proximity, will generate sustained noise as Washington reasserts Monroe Doctrine-style influence. This is a 10–20 year dynamic, not a news cycle.

China consolidates Asia and deepens into MENA via BRI dependencies. Europe is caught in the middle — a contested hybrid between US security dependence and Chinese economic entanglement. The map: USA => Latam; China => Asia/MENA; Europe => hybrid outcome.

For investors operating across Asia-Pacific — as we do at GMG — this is not background noise. It shapes capital flows, currency dynamics, and which markets remain attractive for the next generation of investment. The map being drawn now defines returns for decades.

On The Record: My 13 Calls For 2026 — December 2025

  • Asset markets weak in Q1 — rate stress and inflation anxiety dominate
  • Tariff policy delivers an inflation impulse that markets overprice through H1
  • AI productivity dividend is years away — not a 2026 disinflation story
  • 10-year Treasury breaks 4.50% before mid-year, triggering a policy response
  • Fed deploys 2020-style QE to suppress the long end — first step toward YCC
  • 30-year mortgage rates stabilise 6–7% as YCC caps the long end
  • US real estate experiences one of its best six-month periods in 2H 2026 — YCC + dollar weakness + cap rate compression + international capital inflows
  • DXY breaks below 80, tests 75 in 2H 2026 — the dollar is the arithmetic release valve for contradictory US policy objectives
  • Precious metals continue bull run; aluminium breaks out
  • Legacy software platforms face structural disruption — many will not exist in current form within five years
  • AI data centre capital requirements are a major, underpriced macro headwind — and a significant private credit opportunity in Asia
  • Geopolitical risk premiums rise throughout the year
  • Sphere-of-influence crystallisation: USA => Latam; China => Asia/MENA; Europe navigates a hybrid outcome

"The second half of 2026 rewards those who held their nerve and understood that the pivot — not the panic — is the signal."

FAQ: 2026 Rates, Real Estate And Global Investment Strategy

Q1: Will US home prices rise or fall in 2026?
A: Rise — particularly in 2H. When the Fed implements QE and caps the long end, mortgage rates ease, dollar weakness attracts international capital, and cap rates compress. The structural supply deficit underpins values. For international buyers, 2H 2026 is one of the best risk-adjusted entry points in years.

Q2: What will happen to US mortgage rates in 2026?
A: The 10-year breaks 4.50% in H1, triggering a QE response that brings 30-year mortgages into a 6–7% stabilisation band. No return to 3% — that era was a historical anomaly. But QE-driven suppression unlocks meaningful buyer demand that has been sidelined.

Q3: What is Yield Curve Control and how does it affect real estate?
A: YCC is when a central bank explicitly caps yields at a specific maturity through unlimited asset purchases. When the US moves toward YCC — the logical endpoint of the path I'm mapping — mortgage rates are suppressed, the dollar weakens, and capital rotates into hard assets. For high net worth investors, YCC is the monetary regime that historically produces the strongest real asset returns.

Q4: Is now a good time for foreign nationals to invest in US real estate?
A: The 2H 2026 window will be one of the most compelling entry points for international buyers in years. Dollar weakness provides an effective price discount. QE improves financing terms. The supply deficit supports long-term values. The key is positioning ahead of cap rate compression — waiting until the pivot is fully visible means missing the early move. America Mortgages handles US mortgage financing exclusively for this buyer profile.

Q5: Why will the US dollar fall in 2026?
A: Because it is the only release valve for contradictory US policy objectives. You cannot simultaneously have low rates, GDP growth, manufacturing reshoring, and a strong dollar. Each objective individually requires dollar weakness. The currency absorbs the contradiction so the rest of the system doesn't have to. DXY breaking 80 and testing 75 is not a forecast — it's arithmetic.

Q6: Which software companies are most at risk from AI?
A: Any business whose primary value is the interface layer — the application itself, rather than underlying data, content relationships, or infrastructure. Subscription platforms that aggregate and deliver functionality face structural pressure as AI agents replace the need for dedicated applications. Businesses worth owning are those with irreplaceable data assets or AI infrastructure sitting above and below the disrupted layer.

Q7: What is the data centre investment opportunity in Asia?
A: One of the most significant private credit opportunities we've seen at GMG in a decade. AI compute demand is driving a data centre supercycle across Asia-Pacific. Traditional bank lending is poorly positioned for the structures required. GMG Capital & Advisory is actively participating. The opportunity is real; so is the macro drag on other asset classes as this sector absorbs institutional capital at scale.

CLOSING

These are my December 2025 convictions — on the record, for accountability. I will revisit them in my Q1 2026 update. Until then: watch the 10-year. Stay in hard assets. Don't mistake the panic for the signal.

For high net worth investors and international buyers looking to act on this outlook — through US mortgage financing via America Mortgages or cross-border real estate finance via Global Mortgage Group — I am available to discuss.

Happy Hunting

Donald Klip
Co-founder, Global Mortgage Group, Head GMG Capital Advisory
www.gmg.asia  |  americamortgages.com

DISCLAIMER: The views expressed represent the personal macro investment views of Donald Klip as of December 2025, for informational and entertainment purposes only. Not investment advice. All investments involve risk. Seek independent professional advice before making any investment decision.

Global Real Estate Investors: Where You Can Get Non-Resident Mortgages

Global Real Estate Investors
Globalization network technology perforated paper globe

What You Will Learn

✔ Where non-resident investors can get mortgages across 21 countries.
✔ How GMG approves foreign buyers without local income or credit.
✔ How international mortgage programs work for global investors.
✔ When to use short-term funding before securing a long-term mortgage.
✔ Key global property trends from CBRE and Savills.
✔ Essential FAQs for financing property as a non-resident.

How Non-Resident Mortgages Unlock Global Property Investment

For global investors, real estate remains one of the most reliable ways to build long-term wealth. Markets such as the United States, United Kingdom, Australia, Singapore, and Japan continue to attract foreign buyers seeking stability, rental income, and strategic diversification.

Yet one challenge constantly stands in the way:
Securing financing as a non-resident.

Most banks require local income, domestic tax filings, in-country credit history, and physical residency. For international investors, this creates an enormous barrier, one that prevents access to some of the world’s most attractive property markets.

This is where non-resident mortgages have become indispensable. And it’s where Global Mortgage Group (GMG) has become the global leader, helping investors finance real estate across 21 countries without needing local credit or residency.

Where Global Investors Can Get Non-Resident Mortgages

GMG offers one of the world’s largest international mortgage platforms, providing foreign buyers access to 21 different countries. These programs are designed for investors, expatriates, and high-net-worth clients who want to buy overseas property without navigating restrictive local banking rules.

International Mortgages – 21 Countries GMG Can Finance

North AmericaLATAM & CaribbeanUK & EuropeMENAAsia-Pacific
USPanamaUKUAE (Dubai & Abu Dhabi)Japan
CanadaMexicoFranceIsraelAustralia
Dominican RepublicGermanySingapore
Costa RicaSpainThailand
BelizePortugal
JamaicaItaly
Greece

A full breakdown of product types, loan structures, and residency rules is available in International Residential Mortgages: 21 Countries We Can Finance.

For investors focused on credit diversification, GMG’s lending model also connects seamlessly with its short-term solutions, such as those explained in Short-Term Lending in Singapore: The Smart Investor’s Financing Edge.

Why Non-Resident Mortgages Are in High Demand

The global mortgage landscape has tightened significantly. Traditional banks have become more conservative, stricter with proofs of income, and less willing to underwrite cross-border borrowers.

At the same time, international demand has surged.
Reports from Savills Global Market Outlook show that investors are increasingly expanding into overseas markets for yield, currency stability, and long-term appreciation.

And according to CBRE’s Global Investor Intentions Report, cross-border investment flows are rebounding faster than domestic ones, driven by investors looking for safe-haven markets, rental opportunities, and alternative asset protection.

But to access these markets, investors need financing that banks simply do not offer.
This is exactly where non-resident mortgages become essential, enabling foreign investors to access property markets without meeting restrictive local borrowing criteria.

How GMG’s Non-Resident Mortgages Work

GMG’s programs are designed specifically for foreign nationals and offshore borrowers. Instead of requiring domestic income or credit, GMG underwrites using global earnings, international assets, company structures, and offshore financial profiles.

The process is straightforward, structured, and engineered for foreign buyers. Investors often begin with short-term liquidity solutions such as Singapore bridging loans or global bridging loans before transitioning into permanent financing. GMG explains this approach in detail in Global Bridging Loans in 8 Countries.

When market timing is sensitive, for example, competitive offers in the UK or pre-construction deadlines in Australia, GMG’s ability to pair non-resident mortgages with fast capital becomes a major strategic advantage.

How Global Wealth Uses Cross-Border Financing

High-net-worth families, private investors, and global entrepreneurs increasingly rely on cross-border financing as part of their long-term wealth strategy. Real estate remains a core asset class, especially in periods of currency volatility, shifting interest rates, or geopolitical uncertainty.

GMG has written extensively on global wealth trends, including:

These articles reveal the same conclusion:
Cross-border property financing is no longer optional, it’s a global investment necessity.

The GMG Advantage: Financing Without Borders

Whether you are investing in the U.S., U.K., Australia, Singapore, Japan, or emerging LATAM and Caribbean markets, GMG provides a seamless mortgage experience built specifically for non-resident borrowers.

Our international lending network, cross-border underwriting standards, and deep understanding of foreign national borrowers allow investors to expand globally with confidence.

To explore your non-resident mortgage options:
[email protected]
Contact Us

Learn more about the GMG platform:
About Us

Frequently Asked Questions

Q1. Do I need local income or credit to get a mortgage abroad?

A: No. GMG structures financing using global income, existing assets, corporate earnings, and offshore banking statements. This is precisely why non-resident mortgages are so powerful,  they bypass the traditional bank roadblocks.

Q2. Can I buy investment property as a non-resident?

A: Absolutely. Many GMG clients finance investment units, rental properties, or secondary homes. Even markets like the U.S. and Australia, typically restrictive, offer well-structured non-resident programs.

Q3. Can I combine short-term and long-term financing?

A: Yes. Many investors use a short-term solution first (in competitive markets that require fast liquidity), then refinance into a long-term non-resident mortgage. GMG is one of the few lenders globally that can support both sides of the transaction.

Q4. Do I need to travel to close the loan?

A: In many countries, no. Remote signings, digital identity verification, and international closing agents make it possible to complete the entire process from abroad.

The Ultimate Guide to Getting Property Loans in Europe as a Foreign Investor

Property Loans in Europe
Woman working with finances on the table. Money, papers

What You Will Learn

  • How foreign investors qualify for property loans across Europe
  • Key differences between bank mortgages and private lending in European markets
  • Which European countries are most accessible for non-resident borrowers
  • When bridging loans outperform traditional mortgages
  • Common financing mistakes international buyers make in Europe

Why Europe Remains a Core Market for Foreign Property Investors

Europe continues to attract global investors seeking capital preservation, rental income, and geographic diversification. Despite higher interest rates and tighter bank lending in some regions, demand for European property remains resilient due to stable legal systems, strong tourism economies, and limited housing supply in key cities.

According to Eurostat housing and real estate data, residential demand in major European markets has remained structurally strong even as lending standards tighten. At the same time, guidance from the European Central Bank on credit conditions shows banks becoming more selective, particularly with non-resident borrowers.

This gap between demand and traditional bank financing is where alternative and private lending solutions are reshaping how foreign investors secure property loans in Europe.

Can Foreign Investors Get Property Loans in Europe?

Yes, foreign investors can obtain property loans in Europe, but the process varies significantly by country. Unlike the U.S., Europe does not have a single mortgage framework. Each jurisdiction applies its own rules for residency, income recognition, loan-to-value ratios, and documentation.

In countries like Greece, Portugal, Spain, and parts of France, non-resident mortgages are widely available but often capped at lower LTVs. GMG regularly supports buyers navigating these structures, including transactions detailed in how non-residents secure mortgages in Greece.

In practice, foreign investors who understand these country-level nuances early avoid delays, rejected applications, and unfavorable terms.

Bank Loans vs. Private Property Loans in Europe

Traditional European banks typically offer lower headline rates but apply strict underwriting standards. Non-resident borrowers often face:

  • Lengthy approval timelines
  • Heavy documentation requirements
  • Local income or residency preferences

This is why many global investors turn to private solutions explained in private bridging loans versus bank loans. These structures prioritize asset value, exit strategy, and deal viability over rigid borrower profiles.

For example, a Singapore-based investor acquiring a time-sensitive property in Spain may secure a bridging loan within days, then refinance later once residency or income documentation is aligned.

When Bridging Loans Make Sense for European Property Purchases

Bridging loans are increasingly used across Europe for acquisitions requiring speed or flexibility. These loans are commonly applied for when:

  • A buyer needs to close before bank approval
  • A property requires refurbishment
  • An investor is unlocking equity across jurisdictions

GMG’s global bridging loan platform supports investors across multiple European markets, with structures that align acquisition speed with longer-term financing strategies.

This approach is further expanded in how global bridging loans connect investors across 8 key markets, including Europe, the U.K., and select international hubs.

Market Conditions Driving Demand for Alternative Lending

As European bank lending slows, private credit demand has increased sharply. This trend was highlighted in a recent AP News feature on GMG’s role during regional bank slowdowns, reflecting a broader global shift rather than a temporary cycle.

Foreign investors are no longer waiting for banks to adjust. Instead, they are structuring deals around the certainty of execution.

Choosing the Right European Loan Structure

Selecting the right property loan in Europe depends on:

  • Country-specific regulations
  • Intended property use (investment, second home, redevelopment)
  • Timeline to close
  • Long-term exit strategy

GMG addresses these variables through advisory-led financing, combining insights from Global Property Financing in 2026 with on-the-ground lender access.

Some investors also leverage cross-border strategies by pairing European acquisitions with assets elsewhere, including solutions outlined in GMG’s international loan options.

How GMG Supports Foreign Investors in Europe

Global Mortgage Group operates as a strategic partner, not a single-country lender. Our team helps investors evaluate bank versus private options, assess timing risks, and structure financing across jurisdictions.

Learn more about our platform at Global Mortgage Group or explore our approach and track record on the About GMG page.

How to Continue Your European Property Financing Strategy

Expert Guidance Across European Markets

GMG works with foreign investors purchasing residential and investment properties throughout Europe. Whether you require a traditional mortgage, a private loan, or a bridging solution, our advisory-led model ensures your financing aligns with your broader investment goals.

A Smarter Way to Execute Cross-Border Deals

By combining market intelligence, lender access, and execution speed, GMG helps investors move decisively in competitive European markets. To discuss your strategy, contact our team at [email protected].

Summary

Property loans in Europe remain accessible to foreign investors, but success depends on understanding country-specific rules and choosing the right financing structure. As banks tighten lending, private credit and bridging loans have become essential tools for global investors seeking certainty, speed, and flexibility across European markets.

Frequently Asked Questions

Q1: Can foreign investors get mortgages in Europe without residency?

Yes, many European countries offer non-resident mortgages, though LTVs and documentation vary.

Q2: Are European bank loans better than private loans?

Banks offer lower rates, but private loans provide speed and flexibility.

Q3: Which European countries are easiest for foreign investors?

Greece, Portugal, Spain, and parts of France remain among the most accessible.

Q4: When should investors use bridging loans in Europe?

When timing, refurbishment, or refinancing flexibility is critical.

Q5: Does GMG only operate in Europe?

No. GMG supports property financing across Europe, the U.S., and other global markets.

Foreign Investor? Here’s How to Finance Property in Countries That Welcome Non-Residents

non-resident mortgages

What You Will Learn

  • How foreign investors use non-resident mortgages to buy property without local income or credit.
  • Which countries offer the most mortgage-friendly pathways for overseas buyers.
  • How global lenders evaluate foreign borrowers using international income and assets.
  • When investors use bridging loans + long-term mortgages to compete in fast markets.
  • How GMG structures financing across 21 countries with predictable, cross-border solutions.

Global Property Financing for Non-Resident Investors

Cross-border real estate investment continues to rise, driven by currency diversification, long-term appreciation, and stronger rental yields in mature global markets. Yet the biggest obstacle foreign investors face is not selecting the right market; it’s accessing the right non-resident mortgages.

Many domestic banks still require local income, domestic credit history, in-country tax filings, and physical presence. Foreign investors rarely qualify. That is why GMG’s international mortgage platform has become a critical gateway for global buyers looking to invest abroad without meeting restrictive local banking requirements.

For a full breakdown of eligible markets, refer to: International Residential Mortgages – 21 Countries We Can Finance

Which Countries Welcome Non-Resident Mortgage Financing?

GMG offers access to structured international mortgages across 21 countries, markets characterized by reliable lending ecosystems, transparent property laws, and strong investor demand. These include major hubs such as the United States, the United Kingdom, Australia, Singapore, Canada, Japan, Portugal, Spain, and the UAE.

These destinations stand out because their lending systems are designed to accommodate global buyers with diverse income sources and cross-border financial profiles. Global property trend reports from Savills and CBRE confirm that these countries continue to attract overseas investors due to regulatory stability, liquidity, and rental performance.

Learn more about market access and country-specific programs: International Residential Mortgages – 21 Countries We Can Finance.

How Non-Resident Mortgages Work for Global Investors

Unlike domestic mortgage lending, which relies heavily on local documentation, non-resident mortgage underwriting evaluates a borrower’s international financial footprint. Lenders review global income, overseas assets, international bank statements, and overall liquidity rather than requiring domestic tax filings or in-country credit.

This global-first underwriting structure allows foreign investors to qualify for financing even without local residency. It also ensures that borrowers can purchase investment properties, second homes, or long-term rental units in markets that have historically been considered difficult to enter.

GMG’s cross-border model is specifically built for this purpose, enabling non-residents to borrow in countries with predictable mortgage frameworks while maintaining financial flexibility internationally.

Why Some Markets Are More Mortgage-Friendly Than Others

Countries that welcome non-resident mortgages share several characteristics. They have clear foreign ownership regulations, stable lending environments, strong demand for rental property, and participation from international lenders or specialist mortgage providers. These traits make them well-suited for foreign investors who want structured, long-term financing.

GMG tracks global investment flows closely. Key market shifts and macroeconomic drivers can be explored here:

The Fastest Strategy: Bridging Loans + Non-Resident Mortgages

In competitive markets, investors often need liquidity before a traditional mortgage is finalized. A common solution is to pair a bridging loan with a longer-term non-resident mortgage.

Short-term bridging finance gives investors immediate capital to secure a property, meet developer deadlines, or take advantage of sudden market opportunities. Once the transaction is secure, the borrower transitions into a long-term international mortgage.

Learn more about this financing pathway:

Why investors use this two-step approach:

  • Secure properties with fast-moving timelines
  • Unlock equity from overseas assets to buy abroad
  • Enter stronger markets without cash-flow pressure

This hybrid strategy has become a cornerstone for international buyers seeking premium assets in markets with high demand and limited inventory.

What Lenders Typically Require From Foreign Buyers

Requirements vary by country, but most non-resident mortgage programs follow a similar documentation framework. Lenders usually request:

  • A valid passport
  • Proof of global income or offshore company revenue
  • 3–6 months of international bank statements
  • A clean overseas credit report (if available)

Down payments for non-resident mortgages generally range between 20–40%, depending on the country and property type. GMG helps clients prepare this documentation early to ensure a smoother underwriting process and faster approvals.

How Global Investors Use Non-Resident Mortgages for Wealth Strategy

High-net-worth families and global investors increasingly rely on non-resident mortgages as part of a broader diversification strategy. International real estate provides a hedge against currency fluctuations, inflation, and geopolitical uncertainty. GMG’s insights illustrate this shift in global wealth behavior:

The GMG Advantage: Non-Resident Financing Made Simple

GMG’s international lending platform provides unmatched access to 21 mortgage-friendly countries, bridging solutions, and global underwriting expertise. Whether financing property in the U.S., Europe, Asia-Pacific, or emerging Caribbean markets, GMG ensures investors receive structured, efficient, and competitive lending solutions tailored to their cross-border needs.

For personalized guidance, get in touch at [email protected] or contact us directly.

Frequently Asked Questions

Q1. What makes a country “mortgage-friendly” for non-residents?

A: Countries are mortgage-friendly when they allow foreign buyers to borrow without local income or residency, offer clear ownership rules, and have stable, transparent lending systems. Markets like the U.S., U.K., Australia, Singapore, and Portugal fit this profile.

Q2. Can I get a mortgage if I don’t have local credit in the country I’m buying in?

A: Yes. Lenders use global credit conduct, not local credit scores. An overseas credit report and clean banking history are usually enough for non-resident mortgage programs.

Q3. How do lenders verify income if it comes from abroad or multiple sources?

A: They review your international financial profile, global income, company revenue, rental income, and bank statements, rather than requiring domestic tax filings or in-country employment.

Q4. Should foreign investors pay cash or use financing?

A: Financing is often better. It preserves liquidity, reduces currency risk, and enables diversification. Many investors use a bridging loan first, then refinance into a long-term non-resident mortgage.

How to Finance International Property Without Being a Citizen or Resident

global real estate investments and international mortgages
businessman giving money to his partner while making contract - bribery and corruption concepts.

What You Will Learn

  • How international mortgages allow non-residents to buy property across global markets.
  • Which countries offer predictable, accessible pathways for overseas buyers?
  • How GMG structures non-resident financing using cross-border mortgage and bridging-loan solutions.

Introduction

Buying real estate abroad is no longer limited to citizens or local residents. Global investors,  whether living in Singapore, London, Hong Kong, Dubai, or Toronto, routinely purchase property in markets where they do not live, work, or hold residency. As cross-border investment grows, so does the need for reliable financing, especially international mortgages structured for non-resident buyers.

The reality is that many of the world’s top investment markets welcome foreign buyers, but navigating LTV ratios, income requirements, documentation rules, and currency considerations can be complex without expert guidance. That is where GMG’s experience in structuring international mortgages across 21 global markets becomes essential.

This guide explains how overseas buyers finance property abroad without residency, what lenders typically require and how cross-border risk is evaluated. GMG’s global mortgage and bridging loan solutions to help clients act with speed and clarity.

Global Markets That Welcome Non-Residents

Several major real estate markets allow non-resident buyers to purchase and finance property with international mortgages. These include the U.S., U.K., Australia, Singapore, Thailand, the UAE, Canada, and select destinations in Europe and Latin America.
According to reports by OECD and European Central Bank (ECB), cross-border property flows continue to increase as investors seek diversification, currency hedging, and rental yield opportunities.

These markets stand out because they offer:

  • Clear legal frameworks for foreign ownership
  • Predictable mortgage processes for non-residents
  • Strong rental and capital appreciation fundamentals

Foreign buyers are not required to obtain residency in order to secure financing, especially when working with lenders and brokers accustomed to cross-border underwriting.

For a detailed list of 21 mortgage markets GMG covers, see:
International Mortgage Markets

How Non-Residents Qualify for International Mortgages

While requirements vary by country, most lenders follow a consistent framework when evaluating non-resident buyers. The goal is to verify identity, assess global income, and confirm that the property value aligns with the loan request.

Typical documentation for international mortgages includes:

  • Passport and proof of address
  • Proof of global income (salary, business revenue, dividends, rental income)
  • 3–6 months of international bank statements
  • Credit report from home country (if available)

These requirements are designed to give lenders a clear snapshot of borrower stability, even without local residency or local credit history. GMG helps investors package these documents correctly for each lending jurisdiction to avoid delays.

Loan-to-Value (LTV) Expectations for Non-Resident Buyers

For non-residents using international mortgages, LTV varies widely by market, property type, and borrower profile. However, typical ranges include:

  • U.S.: up to 75–80% for citizens abroad; ~70–75% for foreign nationals
  • U.K.: 60–75% depending on income and country of residence
  • Australia: 60–75% for non-residents
  • Singapore & Thailand: 40–70% depending on currency and lender
  • Europe & Latin America (selected markets): 50–75%

GMG’s lending partners evaluate the property’s rental income, liquidity, and resale demand alongside borrower financials. Investors often combine LTV-based financing with other tools like equity release to enhance purchasing power.

Financing Without Local Credit or Local Income

One of the biggest misconceptions about international mortgages is that buyers must show local income or a local credit score. In reality, most cross-border lenders assess global income from offshore companies, international payroll, consulting revenue, or foreign rental properties.

GMG specialises in helping investors qualify even when:

  • They have no credit footprint in the target country
  • Their income is earned in multiple currencies
  • They hold assets in different jurisdictions
  • They operate through holding companies or family offices

This global underwriting approach is a key reason non-residents can finance property abroad without physical presence or residency ties.

When Bridging Loans Make More Sense Than International Mortgages

In many cases, investors require capital more quickly than a traditional mortgage can provide. That is where bridging loans become an essential alternative. GMG provides fast-access bridge financing in nine countries, enabling clients to secure property, release equity, or fund acquisitions without waiting months for bank approval.

Use cases include:

  • Purchasing before selling an existing property
  • Releasing equity from international homes
  • Renovation, development, or portfolio expansion
  • Time-sensitive investment opportunities

Learn more about GMG’s global bridging loan solutions:

How GMG Helps Non-Residents Finance Global Property

As one of the few firms specializing solely in cross-border financing, GMG structures international mortgages across the U.S., Europe, Asia-Pacific, and the Middle East. Our global underwriting and multi-lender model allows us to:

  • Secure financing for buyers with foreign income
  • Arrange mortgages in 21 countries
  • Provide bridging loans in nine countries
  • Support complex structures (offshore entities, trust ownership, multi-currency income)
  • Offer U.S. mortgage bank solutions for overseas investors

Investors choose GMG because we handle everything end-to-end, qualification, documentation, lender matching, structuring, and closing, even when borrowers never set foot in the country where they’re buying.

Is Financing International Property Right for You?

If you plan to build a global real estate portfolio, diversify currencies, invest for rental yield, or secure housing abroad for your family, international mortgages provide a powerful pathway. With strategic leverage and the right cross-border structure, non-residents can access markets that were previously considered complex or inaccessible.

To explore options or discuss your financing scenario, get in touch with us directly at [email protected] or contact us now.

Frequently Asked Questions

Q1. Can I qualify for international mortgages without having local income or a credit score in the country I’m buying in?

A: Yes. Most lenders offering international mortgages evaluate global income, foreign bank statements, and offshore assets instead of local credit or domestic payslips. GMG works with lenders who use international underwriting standards designed for non-resident borrowers.

Q2. How much down payment do non-residents usually need for international mortgages?

A: Down payments vary by country, but most non-resident international mortgages require 25–40% down. Some U.S. and U.K. lenders may go higher or lower depending on property type, borrower profile, and rental income projections.

Q3. Can international property purchases be completed remotely?

A: Yes. Most markets allow remote applications, digital document submission, and electronic signing for international mortgages. Only a few jurisdictions require one physical meeting or a notarised ID check.

Q4. Do I need residency or a Golden Visa to apply for international mortgages?

A: No. Residency programs like Golden Visas can support long-term planning, but international mortgages do not require citizenship, local residency, or long-term visas. Financing is based primarily on property value, borrower liquidity, and documentation.

Q5. What is the difference between a bridging loan and an international mortgage for non-resident buyers?

A: A bridging loan offers fast, short-term liquidity, ideal for time-sensitive acquisitions or unlocking equity. International mortgages offer long-term financing with structured repayment. Many investors use both: a bridge to secure the property quickly, then refinance into a long-term mortgage.

Live Abroad, Invest Anywhere: Mortgage Solutions for Global Investors

Abroad

What You Will Learn

  • How global mortgage solutions allow investors to buy property anywhere without local income or residency
  • Abroad property financing has become an essential solution for investors and homebuyers seeking overseas real estate opportunities.
  • Which countries are most accessible for non-resident mortgages
  • How bridging loans + mortgages help investors act fast in competitive markets
  • How global lenders underwrite using international income and assets
  • How GMG structures cross-border financing across 21 international markets

Why Global Investors Can Now Buy Property Anywhere

Modern global mortgage solutions allow investors to live in one country and finance real estate in another, even without local income, domestic credit, or residency. According to the Knight Frank Wealth Report and OECD cross-border housing data, demand for international real estate is rising sharply as investors seek diversification, rental yield, and currency stability.

GMG plays a central role in this trend by structuring international mortgages across 21 mortgage-friendly markets, explained in detail in:

This shift means a Singaporean can buy in London, a Dubai investor in Toronto, or a European buyer in Miami, all through structured non-resident lending.

Global Mortgage Solutions: How They Actually Work

Traditional banks require domestic tax filings, local credit reports, and in-country employment. Global mortgage solutions do not.

Instead, non-resident underwriting evaluates:

  • Global income and business revenue
  • International employment contracts
  • Foreign bank statements
  • Overseas assets and liquidity
  • International credit reports (if available)

This model aligns with the financing pathways GMG outlines in:

The result: investors can buy abroad without residency, U.S. W-2s, U.K. payslips, or UAE income.

Where Non-Residents Have the Strongest Financing Access

Certain countries welcome global buyers because their lending ecosystems are built for international participation. Examples include the U.S., U.K., UAE, Canada, Portugal, Australia, and Singapore.

GMG’s full list is here:

These markets offer predictable underwriting, transparent laws, and deep rental demand, key factors confirmed in global studies from Knight Frank and OECD.

The Secret Strategy: Bridging Loans + Long-Term Mortgages

Sophisticated investors rarely rely on traditional mortgage timelines. They pair fast bridging loans with structured long-term mortgages.

Step 1: Bridging Loan for Immediate Liquidity

Used for:

  • Securing a property before competitors
  • Meeting developer deadlines
  • Tapping equity from overseas property
  • Acting quickly in fast markets

GMG provides these short-term solutions globally:

Step 2: Transition to a Long-Term International Mortgage

Once secured, GMG refinances into stable financing that matches the investor’s long-term goals.

This approach is used across eight key markets, illustrated in: How Global Bridging Loans Connect Investors Across 8 Markets

This two-step method is also widely used by high-net-worth families, as shown in: World’s Wealthiest Investors Leveraging Bridging Loans

Real Example: How Global Investors Buy Anywhere

A Singapore-based investor purchased a Miami condo while living in Dubai, without U.S. credit, U.S. tax history, or residency.

GMG structured:

  • A short-term bridging loan to lock in the unit immediately
  • A 70% LTV international mortgage using foreign income
  • A cross-border cash-flow plan for long-term rental stability

This same strategy is applied in Lisbon, Vancouver, Sydney, London, and Dubai.

Investing While Living Abroad: The GMG Advantage

GMG enables global investors to live anywhere while building portfolios across multiple countries. Our platform integrates mortgage planning, cross-border underwriting, and bridging solutions into one seamless process.

Explore additional insights:

GMG structures lending around you, not your location.

Build Your Global Financing Strategy with GMG

Whether you live in Singapore, London, Dubai, Hong Kong, or anywhere in between, GMG provides the global mortgage solutions needed to build an international real estate portfolio.

GMG handles strategy, underwriting, lender selection, and cross-border structuring, so you can focus on finding the right property.

To explore your financing options, contact us at [email protected], or connect with our team through the GMG Contact Page.

✦ Global Experts in International Mortgages & Bridging Loans

Summary

You don’t need local credit, residency, or domestic tax filings to buy international property. With global mortgage solutions, bridging finance, and non-resident underwriting, investors can buy in 21 countries through GMG’s structured, predictable system. Living abroad no longer limits where you invest; GMG makes cross-border ownership accessible and strategic.

Frequently Asked Questions

Q1. Can I finance property abroad without residency?

A: Yes. Most non-resident mortgage programs evaluate global income, international assets, and foreign credit, not residency or local income.

Q2. How fast can a bridging loan be arranged?

A: GMG can structure bridging finance in as little as 24–72 hours, depending on market and documentation readiness.

Q3. Which countries are easiest for non-residents?

A: Markets like the U.S., UAE, Canada, Australia, and Portugal have transparent foreign-buying laws and strong international lending ecosystems.